
Solar Battery Market Report Scope & Overview:
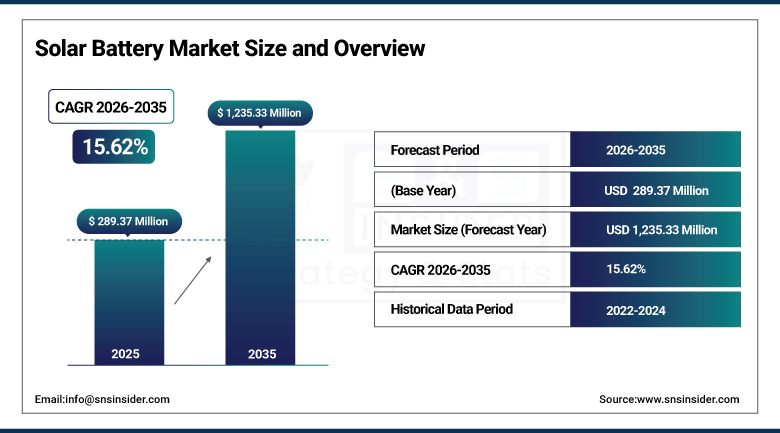
The Solar Battery Market was valued at USD 289.37 Million in 2025 and is expected to reach USD 1,235.33 Million by 2035, growing at a CAGR of 15.62% from 2026-2035.
The Solar Battery Market is experiencing rapid growth as declining battery prices make energy storage an increasingly viable addition to solar installations. BloombergNEF reported in December 2025 that average lithium-ion battery pack prices fell to USD 108 per kilowatt-hour, while stationary storage pack prices reached USD 70 per kilowatt-hour, representing a 45% decline from 2024. Revenue in this market covers batteries used in solar photovoltaic systems, including lithium-ion, lead-acid, flow, and sodium-ion batteries for industrial, commercial, and residential applications. It excludes standalone grid-scale storage without solar integration, inverters, solar panels, and automotive batteries. North America accounts for the largest revenue share, while Asia Pacific is the fastest-growing region.
⮞In June 2026, Tesla held four partner information sessions, two online on 18 and 19 June and two at Tesla Shinjuku in Tokyo on 23 and 24 June, to recruit certified sales and installation partners ahead of the 2026 release of Powerwall 3 in Japan. Powerwall 3 integrates a solar inverter inside the battery, which Tesla says means fewer parts and faster installation.
To Get more information On Solar Battery Market - Request Free Sample Report
Solar Battery Market Trends
-
Shifting from lead-acid to lithium iron phosphate batteries as pack prices fall and cycle life improves.
-
Bundling batteries with hybrid inverters in stackable systems that shorten installation time for solar owners.
-
Enrolling home and business batteries in virtual power plants that earn grid-services revenue.
-
Localizing cell and module assembly to meet incentive content rules and ease supply risk.
-
Introducing sodium-ion and zinc-based chemistries as alternatives for stationary solar storage.
U.S. Solar Battery Market Outlook
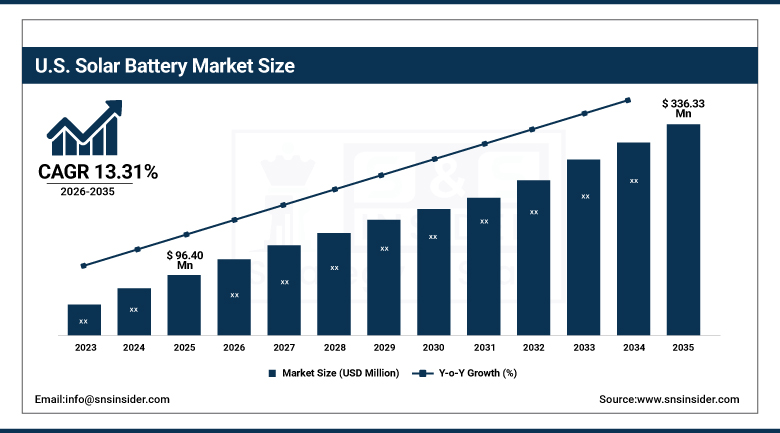
The U.S. Solar Battery Market was valued at USD 96.40 Million in 2025 and is expected to reach USD 336.33 Million by 2035, growing at a CAGR of 13.31% from 2026-2035.
The U.S. Solar Battery Market is expanding at a steady double-digit pace as homeowners and businesses add storage to solar systems for backup power and rate management. The American Clean Power Association and Wood Mackenzie reported in March 2026 that residential storage installations exceeded 800 MW in 2025, up 75 percent from the prior year, with California leading the gains. Demand was pulled forward by the expiring Section 25D residential tax credit, and the same report expects residential storage to decline 2 percent in 2026. Suppliers are therefore stressing U.S. assembly, third-party ownership, and virtual power plant revenue. Texas, Arizona, Illinois, and Puerto Rico rank among the fastest growing regional markets.
⮞In August 2026, Enphase Energy said its IQ Battery 10C and whole-home backup can now be added to existing non-Enphase solar systems across the United States and Canada. The battery stores 10 kWh and delivers 7.08 kW of continuous power, and the IQ Meter Collar, qualified across 71 utilities, enables whole-home backup without a dedicated backup subpanel.
Solar Battery Market Segment Analysis
-
By Battery Type, the Lithium-Ion segment dominated the Solar Battery Market with approximately 51.27% share in 2025, while the Sodium-Ion & Others segment is the fastest growing with a CAGR of approximately 21.38%.
-
By End Use, the Industrial segment dominated the Solar Battery Market with approximately 37.92% share in 2025, while the Residential segment is the fastest growing with a CAGR of approximately 18.46%.
-
By Capacity, the 75-150 AH segment dominated the Solar Battery Market with approximately 42.18% share in 2025, while the Above 150 AH segment is the fastest growing with a CAGR of approximately 18.43%.
-
By Installation Type, the On-Grid segment dominated the Solar Battery Market with approximately 61.38% share in 2025, while the Off-Grid segment is the fastest growing with a CAGR of approximately 17.29%.
By Battery Type, Lithium-Ion Dominates the Solar Battery Market and Sodium-Ion & Others Grows Fastest
Lithium-ion holds the largest revenue pool because lithium iron phosphate cells now give solar owners long cycle life, compact packaging, and steadily lower prices. BloombergNEF put stationary storage packs at USD 70 per kilowatt-hour in 2025, which has pushed lead-acid out of most new installations in developed markets. Enphase, Tesla, SolarEdge, Fronius, and Fortress Power all sell lithium-ion residential systems, and BYD and Huawei offer stackable towers of the same type. Lead-acid still serves price-sensitive off-grid buyers in India and Africa, where Exide and Luminous supply tubular batteries, while flow batteries target long-duration commercial use.
Sodium-ion and other emerging chemistries are advancing fastest from a small base as developers look for alternatives to lithium price swings and supply concentration. CATL signed a three-year order with HyperStrong for 60 GWh of sodium-ion storage batteries, which suppliers read as proof that the chemistry can reach gigawatt-hour scale. Zinc-based systems from Eos Energy address long-duration industrial needs, while sodium-ion cells promise wide temperature tolerance. Adoption remains limited by energy density, with CATL citing roughly 160 Wh/kg for its storage cell, and by thin installer experience. Each new commercial reference lowers perceived risk for solar buyers.
⮞In April 2026, CATL agreed a three-year strategic cooperation with energy storage integrator HyperStrong for 60 GWh of sodium-ion batteries, described as the largest sodium-ion order to date. HyperStrong becomes CATL's first strategic partner for sodium-ion storage, and the deal follows a November 2025 framework under which HyperStrong committed to buy at least 200 GWh of CATL cells from 2026 to 2028.
By End Use, Industrial Dominates the Solar Battery Market and Residential Grows Fastest
Industrial users account for the largest share because factories, telecom sites, mines, and utility-linked plants buy large battery banks to firm solar output and ride through outages. Orders are big and repeat, which favors suppliers with manufacturing scale and service networks. EnerSys supplies industrial lead-acid and lithium batteries for backup and renewable sites, Exide supplies lead-acid units, Eos Energy builds zinc-based systems for multi-hour discharge, and Sungrow, BYD, and CATL sell containerized units that pair with large photovoltaic plants. Masdar's Abu Dhabi project, which combines gigawatt-scale solar with 19 GWh of storage, shows how far industrial buying has moved. Commercial buyers such as shops, offices, and farms form a close second.
Residential demand is growing fastest as homeowners install batteries for backup power, time-of-use savings, and participation in virtual power plants. Germany, Italy, and California remain established markets, while Japan is expanding as Tesla prepares Powerwall 3 for local partners. Installers increasingly favor stackable battery systems from Huawei, BYD, FranklinWH, and sonnen that reduce installation time and labor requirements. However, declining incentives, including the expiry of Section 25D in the United States, contribute to demand fluctuations.
⮞In September 2026, Eos Energy Enterprises received a USD 87 million first advance under the second tranche of its U.S. Department of Energy loan to fund Line 2 at its Thorn Hill facility in Pennsylvania. Line 2 entered commercial production in June 2026, designed for about 2 GWh a year, and the site is expected to reach about 4 GWh across two lines.
By Capacity, 75-150 AH Dominates the Solar Battery Market and Above 150 AH Grows Fastest
Batteries rated 75 to 150 AH lead because they match the typical home and small-business solar system, where one or two 12 volt or 48 volt units cover evening loads and short outages. Installers can stock a few models and replacement is simple, which sustains steady volumes in India, Africa, and Latin America. Exide and Luminous sell tubular solar batteries aimed at homes and small shops, and Victron offers lithium iron phosphate batteries across a wide capacity range for off-grid and marine solar. Buyers in this band value availability, local service, and a familiar form factor more than the highest energy density, so established brands with dense dealer networks keep an advantage.
Units above 150 AH are growing fastest as larger homes, commercial sites, and telecom towers want more stored energy per cabinet and fewer parallel connections. Large-format cells make this possible: BYD's Haohan system uses a 2,710 Ah Blade Battery cell, and Pylontech has introduced 601 Ah cells for its PyOcean system. Samsung SDI sells prismatic cells for solar-linked storage and signed a four-year supply deal worth about USD 1 billion for U.S. projects. Bigger blocks lower cost per kilowatt-hour and simplify installation, but they raise thermal management and fire-safety requirements, which keeps certification a key buying criterion.
⮞In March 2026, Samsung SDI announced a KRW 1.50 trillion, about USD 1 billion, supply agreement through its U.S. affiliate to deliver prismatic energy storage batteries to an unnamed U.S. energy company. Supply starts in 2026 and runs through 2029, beginning with nickel-cobalt-aluminum cells before shifting to lithium iron phosphate, and StarPlus Energy, its joint venture with Stellantis, will produce them at its Indiana plant.
By Installation Type, On-Grid Dominates the Solar Battery Market and Off-Grid Grows Fastest
On-grid systems lead because most solar owners stay connected to the utility and use the battery to shift consumption, ride through outages, and earn payments for grid support. Hybrid inverter and battery bundles from Enphase, SolarEdge, Fronius, Huawei, and Tesla are designed for this connected role. Virtual power plants strengthen the case: sonnen and SOLRITE offer Texas households up to 60 kWh of storage under a battery-only agreement, and Fortress Power systems already take part in 12 programs nationwide. Where tariffs reward evening discharge, as in California and Germany, connected batteries pay back faster, which keeps on-grid installations in front.
Off-grid and weak-grid installations are growing fastest because unreliable networks make solar and storage the primary supply for homes, farms, telecom sites, and small businesses. Pakistan's solar boom has outpaced storage, with an industry official calling for a battery emergency, and CATL-backed CNTE signed a memorandum with Treet Battery in 2026 to explore storage supply. In India and across Africa, Exide and Luminous sell tubular batteries to households, while Victron supplies inverter and battery systems for remote and mobile sites. Falling lithium prices are shifting these buyers toward longer-lasting chemistries, though upfront cost still limits adoption.
⮞In February 2026, sonnen and SOLRITE Energy launched a battery-only virtual power plant agreement in deregulated Texas markets, offering homes up to 60 kWh of sonnen storage with or without rooftop solar. Customers pay a 12 cents per kWh all-in energy rate and a USD 20 monthly fee, and the program targets solar owners whose buy-back plans have ended. Abundance Energy is the retail partner.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
90.43% |
|
Asia Pacific |
China |
47.94% |
|
Europe |
Germany |
36.28% |
|
Middle East & Africa |
South Africa |
44.05% |
|
Latin America |
Brazil |
58.69% |
North America Solar Battery Market Insights
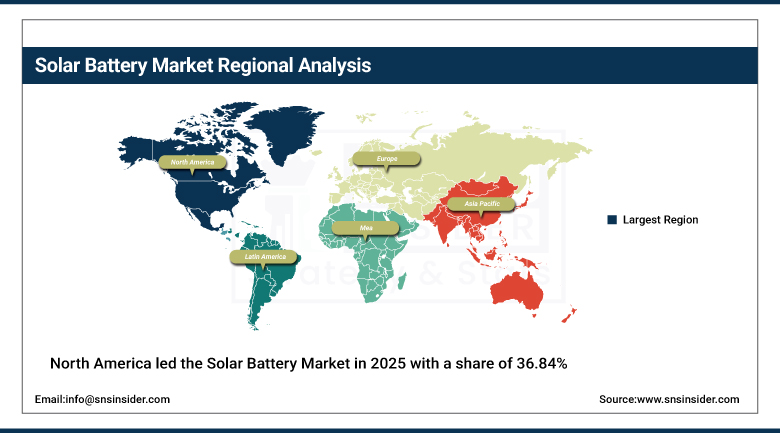
North America led the Solar Battery Market in 2025 with a share of 36.84%, equal to USD 106.60 Million, and is projected to register a CAGR of 13.46% from 2026 to 2035. The United States contributes 90.43% of the regional total, equal to USD 96.40 Million when applied to the rounded North America figure. High retail power rates, outage risk, and storage-friendly tariffs in California and Texas sustain demand, and Wood Mackenzie reported that U.S. residential storage grew 75 percent in 2025. Growth trails Asia Pacific because the base is larger and residential demand is expected to soften as the Section 25D credit expires.
Canada adds steady demand, and sonnen started its first Canadian virtual power plant of networked home batteries in June 2025, while Enphase now supports its IQ Battery 10C in both countries. In the United States, Tesla, Enphase, SolarEdge, Generac, FranklinWH, Fortress Power, and sonnen compete for installer loyalty, and LG Energy Solution's Lansing plant and Samsung SDI's Indiana production add local cell supply for solar-linked storage. Eos Energy builds zinc-based systems in Pennsylvania for industrial buyers, while Mexico adds smaller volumes through commercial rooftop projects.
⮞In August 2026, LG Energy Solution began production at its Lansing, Michigan, campus, its second Michigan plant after Holland, with a target of more than 35 GWh of annual lithium battery capacity. The site makes lithium iron phosphate cells for energy storage systems integrated by LG Energy Solution Vertech, alongside nickel-manganese-cobalt cells for Toyota vehicles, and employs about 900 people.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Solar Battery Market Insights
Asia Pacific accounted for 34.27% of the Solar Battery Market in 2025, equal to USD 99.17 Million, and is the fastest growing region, projected to register a CAGR of 17.82% from 2026 to 2035. Rooftop solar expansion, grid instability, and government subsidies are driving storage attachment across China, Japan, India, and Australia. Australia's Cheaper Home Batteries program, launched on 1 July 2025 with a budget of AUD 7.20 billion, passed 400,000 installations within about ten months, and from 1 May 2026 it tiers the subsidy by battery size, which shapes which products installers recommend.
China remains the largest national market and a major source of cells, with CATL, BYD, Huawei, and Sungrow serving domestic and export demand. India is emerging as a significant growth market, and PM Surya Ghar had commissioned 14.80 GW of rooftop solar by August 2026, the government is considering local content requirements for batteries, and Exide has commissioned its Bengaluru cell plant. Japan is expanding its residential storage market with Powerwall 3, while Australia is served by brands such as FranklinWH, which launched its 15 kWh aPower system in May 2026. Pakistan contributes to regional demand through lead-acid and lithium-ion battery adoption.
⮞In September 2026, Exide Industries disclosed that its subsidiary Exide Energy Solutions had completed Phase I commissioning of a 6 GWh lithium-ion cell manufacturing facility at Devanahalli, Bengaluru. The plant is designed to make cells in multiple chemistries and form factors for electric vehicle and grid storage markets, and Exide Industries invested INR 1 billion in the subsidiary in July 2026.
Europe Solar Battery Market Insights
Europe held 19.73% of the Solar Battery Market in 2025, equal to USD 57.09 Million, and is projected to register a CAGR of 14.86% from 2026 to 2035. SolarPower Europe data show the region added 36 GWh of battery storage in 2025, up 48 percent, led by Germany at 6.60 GWh, the United Kingdom at 5.20 GWh, and Italy at 5 GWh. Distributed solar owners still account for a meaningful part of this demand, although utility-scale projects are taking a growing share of annual installations. Growth is steady because the base is mature and incentives vary by country.
Germany remains the largest national market for solar batteries, with sonnen, SolarEdge, Fronius, Huawei, and BYD competing for homes and small businesses, and SolarEdge opened orders for its Nexis system in Germany in March 2026. The United Kingdom and Italy are expanding quickly, and Fronius makes its Reserva Pro battery in Europe, which appeals to buyers wary of import dependence. Bulgaria and Ukraine add distributed storage demand, while France and Spain contribute smaller volumes tied to rooftop and commercial projects.
⮞In March 2026, Fronius announced it would show its Reserva Pro high-voltage battery at Intersolar Europe in Munich from 23 to 25 June. The DC-coupled battery is made in Europe, expands from 12 to 32 kWh per tower and up to 128 kWh in parallel, and pairs with the Fronius GEN24 Plus and Verto Plus inverters, with backup power and black start functions.
MEA & Latin America Solar Battery Market Insights
The Middle East & Africa accounted for 5.71% of the Solar Battery Market in 2025, equal to USD 16.52 Million, and is projected to register a CAGR of 17.09% from 2026 to 2035, the second fastest rate among regions. South Africa leads on rooftop solar with batteries as households and businesses avoid outages, and Gulf states are building very large solar-plus-storage projects. Sungrow won a 7.80 GWh battery supply deal in Saudi Arabia in 2024, BYD holds a 12.50 GWh agreement with Saudi Electricity Company, and both companies are supplying Masdar's Abu Dhabi round-the-clock project. Smaller African markets add distributed demand.
⮞In July 2026, BYD Energy Storage agreed to supply more than 11 GWh of storage for Masdar's Abu Dhabi round-the-clock renewable project, a single 1,644 MW storage station. BYD will deliver its Haohan system, which uses a 2,710 Ah Blade Battery cell, together with its GC Master energy management system, and the project pairs gigawatt-scale solar with 19 GWh of battery storage.
Latin America held 3.45% of the Solar Battery Market in 2025, equal to USD 9.98 Million, and is projected to register a CAGR of 15.65% from 2026 to 2035. Brazil leads, where distributed solar is widespread and suppliers are now adding batteries. Sungrow, which has sold 16.50 GW of inverters in Brazil since 2017, introduced its MBL battery and MGRL hybrid inverters there in 2026, and Huawei launched its LUNA 2000 residential battery in Sao Paulo in October 2024. BYD sells residential solar kits through 233 Brazilian dealerships, a channel that could later carry batteries. Chile and Mexico add commercial demand.
⮞In August 2026, Sungrow expanded its Brazilian residential storage portfolio with the MBL battery, developed in-house for direct integration with its inverters, and the MGRL single-phase hybrid inverters rated from 5 kW to 10 kW. The company also introduced MGSplit for split-phase grids, and the first commercial import shipments of MGRL units were at sea bound for local distributors.
Market Dynamics
Growth Drivers: Falling Battery Prices and Rising Backup and Self-Consumption Demand
Falling battery prices are the first driver, because storage cost is the main barrier between a solar owner and a complete system. BloombergNEF reported that average lithium-ion pack prices reached USD 108 per kilowatt-hour in 2025, 8 percent below 2024, and that stationary storage packs fell 45 percent to USD 70 per kilowatt-hour. Lower cell costs allow suppliers such as BYD, Huawei, and SolarEdge to launch modular towers with longer warranties, and they shorten payback for commercial and industrial buyers who size batteries to cover evening peaks. Each price step widens the group of solar owners for whom storage makes financial sense.
Rising demand for backup power and self-consumption forms the second driver, as outages, tariffs, and subsidies push owners to store their own solar output. Australia's Cheaper Home Batteries program passed 400,000 installations in about ten months, and Wood Mackenzie reported that U.S. residential storage grew 75 percent in 2025. In India, PM Surya Ghar had commissioned 14.80 GW of rooftop solar by August 2026, creating a large base of systems that can add batteries later. Households with net metering changes or unreliable grids increasingly treat the battery as part of the solar purchase rather than an upgrade.
⮞In June 2026, Huawei Digital Power launched its LUTERRA S2 residential solar and storage system at Intersolar Europe, combining a three-phase silicon carbide hybrid inverter with vertically stacked battery banks of up to four 5 kWh or 7 kWh packs. Huawei claims installation in under 10 minutes without on-site wiring, with commercial availability in Europe planned for November 2026.
Restraints: Incentive Uncertainty and Policy Shifts and Cell Supply Concentration and Safety Concerns
Incentive uncertainty and policy shifts restrain growth, because many solar battery purchases depend on tax credits, subsidies, or tariff rules that change on short notice. Wood Mackenzie expects U.S. residential storage to decline 2% in 2026 after the Section 25D credit expires, and Australia has tiered its home battery subsidy by size from 1 May 2026. India is weighing local content rules for batteries under the next phase of PM Surya Ghar, which could raise costs for importers. Buyers delay decisions when rules are unclear, and installers carry the inventory risk.
Cell supply concentration and safety concerns form the second restraint. Most lithium cells for solar storage come from a small group of Asian producers, and Wood Mackenzie reports that India has only 2 GWh of commissioned cell capacity in 2026 against a demand pipeline of roughly 260 GWh. Local assembly in the United States and Europe is growing but still depends on imported materials. Fire-safety rules, long certification cycles, and installer training needs add cost, and a single high-profile incident can slow adoption in a region for months.
Opportunities: Virtual Power Plants and Grid Services and Localized Manufacturing and New Chemistries
Virtual power plants and grid services open a larger revenue pool for suppliers that can aggregate batteries. Fortress Power systems already participate in 12 programs across the United States, sonnen runs networked fleets in Texas, Canada, Germany, and Belgium, and Flip Energy now links Fortress batteries to additional utility programs. Owners earn payments for discharging at peak times, which shortens payback and gives manufacturers recurring software income beyond the hardware sale. Utilities facing data center and population growth are increasingly willing to pay for distributed capacity.
Localized manufacturing and new chemistries provide a second path. SolarEdge assembles its Nexis and Home Battery products in the United States, Fronius makes Reserva Pro in Europe, and Exide is building lithium-ion cell capacity in India, all of which help buyers meet content rules and shorten delivery times. Sodium-ion and zinc-based systems from CATL and Eos Energy offer ways to diversify away from lithium, and they suit stationary solar storage where weight matters less than cost, safety, and cycle life.
⮞In July 2026, SolarEdge opened U.S. orders for Nexis, a home solar and battery platform that debuted in Germany. Battery capacity ranges from 5 to 80 kWh in lightweight modules that click together without wiring, installation takes under 30 minutes according to SolarEdge, and the system is U.S.-made, which may help projects meet local content requirements.
Recent Developments:
-
June 2026: BYD launched Battery-Box Mega at Smarter E Europe in Munich, a DC-coupled lithium iron phosphate residential system with 12.50 kWh modules stacked into configurations from 62.40 kWh to 262 kWh. The system pairs with the Power-Box TH inverter and carries an IP66 rating, and BYD also introduced a Smart Ecobox and a Backup-Box for the home.
-
May 2026: FranklinWH introduced an enhanced aPower home battery in Australia and New Zealand, lifting usable capacity from 13.60 kWh to 15 kWh and warrantied throughput from 43 MWh to 60 MWh at an unchanged price. The company said the 15 kWh configuration fits the updated Cheaper Home Batteries program that took effect on 1 May 2026.
-
July 2026: Fortress Power partnered with Flip Energy to widen access to virtual power plant and grid services programs across the United States and Puerto Rico. Fortress systems already participate in 12 programs, including LUMA's Clean Energy Program in Puerto Rico and Rocky Mountain Power's Wattsmart Battery Program.
Solar Battery Market Key Players are:
-
Tesla, Inc. (Powerwall)
-
BYD Company Limited (Battery-Box)
-
Contemporary Amperex Technology Co., Limited (CATL)
-
Huawei Technologies Co., Ltd. (LUNA2000)
-
Sungrow Power Supply Co., Ltd.
-
Enphase Energy, Inc.
-
SolarEdge Technologies, Inc.
-
Generac Holdings Inc. (PWRcell)
-
Fronius International GmbH (Reserva)
-
FranklinWH Energy Storage Inc.
-
Fortress Power LLC
-
Samsung SDI Co., Ltd.
-
LG Energy Solution, Ltd.
-
Pylon Technologies Co., Ltd. (Pylontech)
-
Eos Energy Enterprises, Inc.
-
EnerSys
-
Exide Industries Limited
-
Luminous Power Technologies Pvt. Ltd.
-
Panasonic Corporation
-
Saft (TotalEnergies SE)
Solar Battery Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 289.37 Million |
| Market Size by 2035 | USD 1,235.33 Million |
| CAGR | 15.62% from 2026-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Battery Type: Dominant – Lithium-Ion (51.27% share in 2025); Fastest-Growing – Sodium-Ion & Others (CAGR 21.38%) • By End Use: Dominant – Industrial (37.92% share in 2025); Fastest-Growing – Residential (CAGR 18.46%) • By Capacity: Dominant – 75-150 AH (42.18% share in 2025); Fastest-Growing – Above 150 AH (CAGR 18.43%) • By Installation Type: Dominant – On-Grid (61.38% share in 2025); Fastest-Growing – Off-Grid (CAGR 17.29%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Tesla, Inc. (Powerwall), BYD Company Limited (Battery-Box), Contemporary Amperex Technology Co., Limited (CATL), Huawei Technologies Co., Ltd. (LUNA2000), Sungrow Power Supply Co., Ltd., Enphase Energy, Inc., SolarEdge Technologies, Inc., Generac Holdings Inc. (PWRcell), Fronius International GmbH (Reserva), FranklinWH Energy Storage Inc., Fortress Power LLC, Samsung SDI Co., Ltd., LG Energy Solution, Ltd., Pylon Technologies Co., Ltd. (Pylontech), Eos Energy Enterprises, Inc., EnerSys, Exide Industries Limited, Luminous Power Technologies Pvt. Ltd., Panasonic Corporation, Saft (TotalEnergies SE) |

Frequently Asked Questions
Key players include Tesla, Inc., BYD Company Limited, CATL, Huawei Technologies Co., Ltd., and Sungrow Power Supply Co., Ltd., among others.
Virtual power plant and grid-services revenue, localized cell and module manufacturing, and the arrival of sodium-ion and zinc-based chemistries represent the primary opportunities.
Growth is primarily driven by falling lithium-ion battery prices, combined with rising demand for backup power and self-consumption among solar owners.
By Battery Type, Lithium-Ion dominated the market with approximately 51.27% share in 2025, reflecting long cycle life, compact packaging, and steadily lower prices.
North America dominated the market with approximately 36.84% share in 2025, driven by high retail power rates, outage risk, and storage-friendly tariffs in California and Texas.
