
Functional Service Providers (FSP) Market Report Scope and Overview
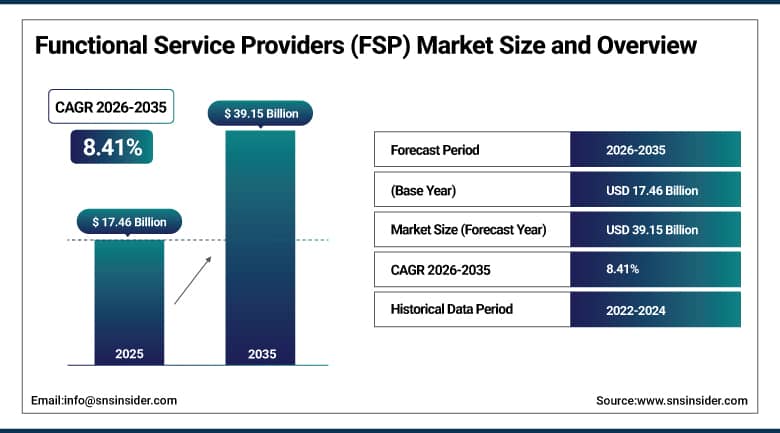
The Functional Service Providers (FSP) Market was valued at USD 17.46 Billion in 2025 and is estimated at USD 18.93 Billion in 2026. The market is forecast to reach USD 39.15 Billion by 2035, registering a CAGR of 8.41% from 2026 to 2035. Sponsors in the pharmaceutical and biotechnology sectors engage dedicated teams for clinical monitoring, data management, biostatistics, and safety work instead of outsourcing whole studies. Rising trial complexity and cost pressure support the model. North America accounted for the largest regional share at 41.38% in 2025, while Asia Pacific is expected to expand fastest.
To Get More Information On Functional Service Providers (FSP) Market - Request Free Sample Report
Key Market Trends & Insights
-
By service type: Clinical monitoring held the largest market share of 25.73% in 2025.
-
By development stage: Clinical development held the largest market share of 70.46% in 2025.
-
By therapeutic area: Oncology held the largest market share of 29.14% in 2025.
-
By end user: Pharmaceutical companies held the largest market share of 53.46% in 2025.
-
North America accounted for the largest regional share of 41.38% in 2025.
-
Asia Pacific is projected to register the fastest regional CAGR of 10.03% from 2026 to 2035.
-
The U.S. is the leading country market, supported by the largest concentration of sponsor headquarters, clinical trial activity, and experienced trial professionals.
Growth Outlook
Regulators are placing greater weight on sponsor oversight of outsourced work, and this favors dedicated functional teams that report directly into sponsor processes. In September 2025, the U.S. Food and Drug Administration published the final ICH E6(R3) good clinical practice guideline, which keeps sponsors accountable for trial conduct when tasks are delegated to contract research organizations and other vendors. Sponsors respond by keeping control of strategy and quality while buying capacity for specific functions, and providers that document oversight clearly gain an advantage in selection.
Trial design is also changing the type of staff that sponsors need. Adaptive designs, decentralized elements, real-world data, and artificial intelligence tools raise demand for biostatisticians, programmers, data managers, and safety specialists who can work inside sponsor systems. Hiring and retaining these experts is costly and slow, and workloads rise and fall between study phases. Providers supply scalable teams on multi-year agreements, which lets sponsors adjust resources without permanent headcount and keep programs on schedule. Sponsors also benefit from lower fixed costs.
Market Dynamics
Driver: Rising Trial Complexity, Cost Pressure, and Demand for Flexible Capacity Support Functional Outsourcing
Drug developers face rising costs and longer timelines, and clinical operations budgets are under constant review. Functional outsourcing lets a sponsor retain control of study strategy while contracting a dedicated team for monitoring, data management, or biostatistics, and it avoids the markup associated with full-service contracts. Large pharmaceutical companies increasingly maintain preferred provider panels and sign multi-year agreements with a small group of partners, which creates stable volumes for providers. Smaller sponsors use the model to reach specialist skills without building internal departments. Providers that can show strong retention, predictable quality metrics, and rapid onboarding of replacement staff are favored when sponsors renew or expand these panels.
Technology adds to the case for outsourcing. Providers invest in clinical data platforms, risk-based monitoring tools, and artificial intelligence for coding, query management, and safety case processing, and they spread these costs across many clients. Large providers now package technology with dedicated teams and move away from pricing by headcount, which gives sponsors measurable productivity targets. Sponsors gain access to modern tools without separate procurement projects, which supports long-term renewals. Data partnerships that link real-world records to trial planning add further capability and help providers support site selection and protocol design. Sponsors value these tools because they shorten start-up and improve enrollment forecasting.
Restraint: Sponsor Oversight Burden, Data Security Duties, and Pricing Pressure Limit Margins
Functional teams work inside sponsor systems, so sponsors must manage resourcing, training, and quality across many individuals instead of one study team. This oversight burden can offset the savings of the model, and some sponsors return to full-service contracts for large programs that need a single accountable vendor. Providers also carry the cost of replacing departing staff, and high turnover among clinical research associates and programmers can disrupt continuity, harm relationships, and expose both parties to compliance findings during inspections. Sponsors also worry about knowledge loss when experienced team members rotate between clients, so contracts increasingly include retention terms and detailed transition plans.
Data security and privacy rules add cost. Teams handle personal health data under HIPAA, GDPR, and national laws, and providers must run secure environments, audit trails, and validated systems. Competitive intensity is also high, and sponsors use vendor panels to negotiate lower rates, which compresses margins for smaller providers. Mergers among large contract research organizations create further uncertainty about staffing and service levels, and sponsors may diversify their provider base as a result. Pricing discussions have grown tougher as procurement teams benchmark rates across providers and regions, and providers must invest in automation to protect margins while delivering the same quality at a lower unit cost to clients.
Opportunity: AI-Enabled Delivery, Hybrid Models, and Emerging Market Hubs Open New Revenue
Outcome-based and hybrid arrangements offer a new route for growth. Sponsors increasingly combine functional teams with full-service support for selected studies, and providers that can price against deliverables instead of headcount are positioned to win larger scopes. Artificial intelligence tools for medical coding, data cleaning, and safety case intake allow providers to raise productivity, and those that share the gains with clients can differentiate from rivals. Integrated platforms that link monitoring, data, and safety teams also improve visibility. Providers can also bundle analytics and consulting with functional teams, which raises revenue per client and strengthens relationships beyond transactional staffing. Early adopters of such offers report greater sponsor loyalty.
Geographic expansion adds further room. Providers are building delivery hubs in India, Eastern Europe, China, and Latin America, which offer skilled graduates at lower cost and support round-the-clock coverage. Faster regulatory reviews in markets such as China and India make local trial activity more attractive, and sponsors need regional teams to run studies. Biotechnology start-ups, which outsource most functions, form a growing client base for flexible teams. Partnerships with local universities and training programs also help providers build talent pipelines, which reduces hiring costs and supports expansion into regions where experienced clinical research professionals are scarce. Providers that train staff locally can also respond faster when sponsors add new sites or countries mid-study.
Market Characteristics & Concentration
The Functional Service Providers (FSP) Market is Moderately Fragmented. Large contract research organizations such as IQVIA, ICON, Thermo Fisher Scientific through its PPD business, Parexel, Syneos Health, and Fortrea hold the largest FSP books, while specialists including Precision for Medicine, Cytel, Premier Research, Quanticate, and ProPharma compete in functions such as biostatistics, data management, and clinical operations. Sponsors typically use several providers. No single provider controls the market, and contract values range widely across functions and sponsors.
Consolidation is continuing. In 2026, Worldwide Clinical Trials acquired Catalyst Clinical Research, Parexel acquired the pharmacovigilance technology firm Vitrana, and Syneos Health bought a Chinese contract research organization, while McKesson agreed to acquire the parent of Precision for Medicine. Providers pursue acquisitions to add technology, regional reach, and therapeutic expertise, which raises barriers for sub-scale firms. Acquirers are targeting biostatistics, regulatory, and AI-driven safety capabilities that complement their existing delivery models and widen the services they can offer under one agreement.
Competition centers on talent quality, technology, and pricing models. Providers differentiate through proprietary platforms, dedicated sponsor teams, and global delivery centers, and they add artificial intelligence to raise productivity. Established relationships and preferred provider status make renewals common, so new entrants usually win business through specialist skills such as biostatistics or oncology. Regional delivery centers in India, Eastern Europe, and China give providers a cost advantage, and sponsors value teams that can work across time zones.
Analyst Perspective
Functional outsourcing is shifting from a staffing model to a managed capability model in which providers combine skilled teams with technology and share accountability for results. Trial complexity, cost pressure, and tighter oversight rules will keep sponsors using multiple partners, while consolidation among large providers reshapes competition. Companies that show productivity gains, strong governance, and flexible commercial terms are best placed to win the largest agreements. An SNS Insider Analyst, Santosh Bhul, commented, "Sponsors want the control of an internal team with the scale of a global partner. Providers that deliver both, supported by technology and clear accountability, will lead the market."
Segment Analysis
Service Type Insights
Clinical monitoring accounted for 25.73% of the market in 2025. Sponsors contract dedicated monitors to visit sites, verify source data, and track protocol compliance, and these roles are the largest recurring headcount in trial operations. Demand for experienced monitors remains high because study volumes and site numbers continue to grow. Risk-based monitoring reduces site visits, but remote review and oversight tasks keep teams busy, and sponsors prefer stable partners that can supply trained staff in many countries at short notice. Long assignments and low staff turnover are valued highly by sponsors in these roles.
Data management is anticipated to grow at the fastest CAGR of 9.97% from 2026 to 2035. Trials generate data from electronic records, wearables, imaging, and laboratory feeds, and cleaning and aligning these sources requires specialist teams. Providers apply automation and artificial intelligence to speed up query resolution and coding. Biostatistics and programming, medical writing, pharmacovigilance, and regulatory affairs complete the mix, and each offers steady demand because they depend on skills that sponsors find hard to hire. Providers that can supply certified data managers with experience in several electronic data capture systems attract repeat assignments from sponsors.
Development Stage Insights
Clinical development accounted for 70.46% of the market in 2025. Phase 1 to Phase 3 programs need the largest number of monitors, data managers, statisticians, and safety staff, and sponsors maintain dedicated teams across the life of each program. Pharmaceutical companies fund large pipelines, and biotechnology start-ups run many early studies with small internal teams. Multi-year agreements with preferred providers keep volumes steady even as individual studies start and finish. Providers also supply medical writers and regulatory staff during this stage to prepare protocols, study reports, and submission documents, which extends the scope of work beyond monitoring and data tasks.
Post-approval work is projected to register the fastest CAGR of 9.58% from 2026 to 2035. Regulators expect continued safety monitoring, registries, and real-world evidence studies after launch, and sponsors need pharmacovigilance and medical affairs staff for long periods. Providers offer case processing, signal detection, and periodic reporting at scale. Growth in approved products, including cell and gene therapies with long-term follow-up duties, expands the workload that needs specialist teams. Contracts for such work are often longer than those in clinical development, because safety obligations continue for the lifetime of a product. Providers with global case processing capacity benefit most.
Therapeutic Area Insights
Oncology held the largest share of 29.14% in 2025. Cancer programs make up the largest portion of the development pipeline worldwide, and they involve complex protocols, biomarker testing, and intensive data collection that require specialist monitors and statisticians. Sponsors depend on providers with oncology experience, and the arrival of combination regimens and cell therapies increases the number of studies that need dedicated functional teams over long follow-up periods. Providers with oncology specialization, such as Catalyst Clinical Research within Worldwide Clinical Trials, are valued for their familiarity with tumor assessment criteria and regulatory expectations.
Immunology and inflammation are expected to register the fastest CAGR of 10.74% from 2026 to 2035. Programs in autoimmune, dermatologic, and respiratory conditions are expanding as sponsors pursue new mechanisms and larger patient populations, and these trials often enroll many sites. Cardiovascular, central nervous system, and infectious disease programs also generate steady outsourcing demand, particularly for biostatistics, data management, and safety monitoring across global studies. Sponsors also value statistical teams that can handle adaptive designs and complex endpoints, which are common in immunology programs with several treatment arms. Providers with deep experience in these areas win repeat assignments.
End User Insights
Pharmaceutical companies represented the largest share of 53.46% in 2025. Large sponsors run broad portfolios and prefer to keep strategic control while contracting functions to preferred providers on multi-year terms. Procurement teams use vendor panels to negotiate rates, and providers with global delivery capacity and strong quality records secure the largest contracts. Established relationships mean that renewals are common, which provides stable revenue for the leading providers. Pharmaceutical companies also account for much of the demand for pharmacovigilance and regulatory support, since large marketed portfolios require continuous safety reporting and submissions. Global providers with local presence are preferred.
Biotechnology companies are projected to register the fastest CAGR of 10.12% from 2026 to 2035. Funded start-ups run numerous early and mid-stage trials with small internal teams and rely on providers for monitoring, data management, and statistical work. Medical device companies and academic and research institutes form the remainder and adopt functional models as regulatory expectations for clinical evidence rise and as grant funded studies grow larger and more complex. Providers often tailor smaller team structures and pricing for these clients, which allows flexible scaling as funding milestones are reached. Short onboarding times matter.
Regional Insights
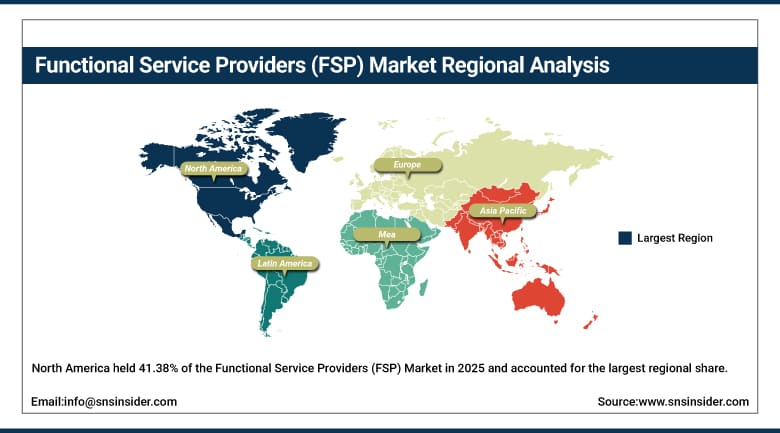
North America held 41.38% of the Functional Service Providers (FSP) Market in 2025 and accounted for the largest regional share. The region hosts the largest concentration of sponsor headquarters, the heaviest trial activity, and a deep pool of experienced clinical research professionals. Regulators expect sponsors to keep close oversight of the vendors that support their studies. Canada adds a smaller base of trial activity, and Mexico is reported within Latin America in this analysis. Sponsors also value the depth of local talent.
Get Customized Report as Per Your Business Requirement - Enquiry Now
U.S. Functional Service Providers (FSP) Market
The U.S. Functional Service Providers (FSP) Market was valued at USD 6.62 Billion in 2025 and is projected to expand at a CAGR of 8.53% from 2026 to 2035. Large pharmaceutical and biotechnology sponsors in the country run extensive pipelines, and they contract dedicated teams for monitoring, data management, biostatistics, and pharmacovigilance. Tight labor markets for clinical research associates and programmers keep demand for providers high. Providers also benefit from the large number of academic medical centers and community oncology networks that take part in industry studies.
In June 2026, the U.S. Department of Health and Human Services announced Operation TrialBlazer, and the Food and Drug Administration opened a request for information on an expedited investigational new drug pilot that includes contract research organizations. These initiatives aim to streamline trial start-up and could raise demand for providers with strong regulatory and operations teams. Consolidation is also active, with McKesson agreeing in August 2026 to acquire Precision Medicine Group for about USD 2.25 Billion.
Europe Functional Service Providers (FSP) Market
Europe had a market share of 28.64% in 2025, with Germany, the UK, France, and Italy making up the lion's share. This area conducts a considerable portion of global trials and boasts some of the top providers; here, sponsors rely on functional teams for monitoring, biostatistics, and safety. In January 2025, the Clinical Trials Regulation became fully applicable, resulting in the transfer of over 5,000 trials to the Clinical Trials Information System, thus increasing the demand for regulatory and data specialists. Cross-border trials need multi-national authority aware teams.
The UK has a different framework. New clinical trials regulations were introduced in April 2026, and the Health Research Authority and the Medicines and Healthcare products Regulatory Agency highlighted reduced combined review timelines. Germany, France, Spain, and Italy continue to dominate in the trials sphere, while Eastern Europe offers affordable centers for data management, programming, and monitoring support services. Combined review procedures and local ethics submission are typical, thus, adding to the workload of the regulatory affairs department.
Asia Pacific Functional Service Providers (FSP) Market
Asia Pacific is forecasted to experience the fastest regional CAGR of 10.03% from 2026 to 2035, and the region represented 22.15% of the market in 2025. Demand from China, India, Japan, South Korea, and Australia is fueled by rising trials activity and increasing local sponsors. On September 2025, the China National Medical Products Administration released Announcement No. 86, according to which 30-working-day review of investigational applications is allowed for qualified innovative drugs. The rapid increase in the local pharmaceutical R&D activity is driving up the number of regional sponsors outsourcing.
On January 2026, India updated its New Drugs and Clinical Trials Rules with simplifying requirements for test licenses, while reducing the application review period from 90 to 45 working days. Moreover, India has delivery centers of significant size providing services in data management, programming, and pharmacovigilance. Japan and South Korea contribute demand through monitoring and regulatory support, while Australia stays an attractive destination for early-phase trials. Providers leverage the Asia Pacific market for site networks and patient recruitment services, particularly for oncology and rare diseases studies.
Latin America Functional Service Providers (FSP) Market
The Latin American region had a market share of 4.68% in 2025, driven by Brazil, whereas Mexico, Argentina, and Colombia added their contribution to the market demand. The large size of the patient population and the growth of the site network attract the global sponsors to conduct late-stage research. Local teams conduct monitoring, submission to regulatory authorities, and pharmacovigilance services. The sponsors value the diversity of patients in this region and cost advantage, while the regional site networks have grown in the areas of oncology, infectious disease, and cardiovascular research. Knowledge of the regional language and familiarity with regional ethics are among the key selection factors for providers.
Brazil introduced Decree 12,651 in October 2025 to regulate the national clinical research law, providing a 15-day priority ethical review for strategic projects. It will allow decreasing the start-up period in the country and enhancing its position in relation to global trials. At the same time, the site capacity in Mexico, Argentina, and Colombia is being expanded, requiring the functional team familiar with the local regulatory process. The providers having regional offices will be able to capitalize on the additional sites and countries included in the global programs.
Middle East & Africa Functional Service Providers (FSP) Market
The Middle East & Africa accounted for 3.15% of the market in 2025, led by Saudi Arabia, the United Arab Emirates, Israel, Egypt, and South Africa. Trial activity is smaller than in other regions, but governments are investing in research infrastructure and clinical trial regulation, and sponsors use the region to reach diverse patient populations. Several countries in the Gulf promote clinical research as part of national health transformation strategies, which attracts sponsors seeking diverse populations and fast recruitment.
Providers supply regional monitoring, regulatory, and safety support through local offices and partnerships. Demand rises as hospitals and research centers in Gulf countries seek international studies, and South Africa remains a hub for trials in infectious diseases and oncology. Skilled staff are limited, so global providers often supply teams that travel or work remotely. Providers also work with academic hospitals to build local capacity in good clinical practice and data management training, which supports longer-term growth in the region.
Key Functional Service Providers (FSP) Market Company Insights
Companies in the functional service providers market are focusing on artificial intelligence enabled delivery, outcome-based pricing, and acquisitions that add technology and regional reach. Large contract research organizations compete with biostatistics and data specialists, and sponsors increasingly pair several providers across functions under multi-year agreements.
Key Functional Service Providers (FSP) Companies:
-
IQVIA Holdings Inc.
-
Parexel International Corporation
-
ICON plc
-
Syneos Health, Inc.
-
Thermo Fisher Scientific Inc. (PPD Clinical Research)
-
Fortrea Holdings Inc.
-
Labcorp Drug Development (Labcorp Holdings Inc.)
-
Precision for Medicine (Precision Medicine Group)
-
Cytel, Inc.
-
Premier Research Group Limited
-
Worldwide Clinical Trials, Inc. (including Catalyst Clinical Research)
-
Quanticate International Limited
-
ProPharma Group Holdings, LLC
-
Aixial Group (including Cmed)
-
Tigermed Consulting Co., Ltd. (Hangzhou Tigermed)
Recent Developments
-
In September 2026, Parexel launched FSP Integrated Solutions, an offering that combines more than 8,000 functional resources with its ParexelAI platform. The model moves away from headcount-based pricing and creates a new leadership role for integrated solutions.
-
In September 2026, Fortrea agreed to acquire the early phase services division of Worldwide Clinical Trials for about USD 45.00 Million, adding clinical pharmacology and bioanalytical laboratory operations.
-
In August 2026, McKesson agreed to acquire Precision Medicine Group, the parent of Precision for Medicine, for about USD 2.25 Billion. The transaction is subject to regulatory clearance.
-
In June 2026, ICON named Microsoft as its preferred technology partner to power AI-enabled clinical research. The collaboration covers the ICON Orbis platform and the use of Microsoft Copilot tools across study delivery.
-
In April 2026, Thermo Fisher Scientific PPD clinical research business announced a collaboration with HealthVerity to expand real-world data capabilities. The partnership draws on de-identified records for about 270 million U.S. patients to support site selection and study start-up.
-
In April 2026, Worldwide Clinical Trials and Medidata expanded their partnership, and Worldwide became the first global contract research organization on the Medidata Plus platform.
-
In April 2026, Parexel acquired Vitrana, an AI-driven pharmacovigilance technology company, to add patient safety automation. The financial terms were not disclosed.
-
In March 2026, ICON and Advarra signed a definitive agreement to introduce a research-ready connected site network that is designed to speed up study start-up and enrollment.
-
In March 2026, Syneos Health completed the acquisition of Bestudy Medical Technology, a Shanghai-based contract research organization, to expand its operations in China. The business will keep its standalone brand.
-
In February 2026, Thermo Fisher Scientific PPD clinical research business and Datavant announced a collaboration to link real-world data with clinical development programs through privacy-preserving technology.
-
In January 2026, Worldwide Clinical Trials announced the acquisition of Catalyst Clinical Research, an oncology-focused contract research organization and FSP provider, and completed it in February 2026. The combined organization has about 4,400 employees in more than 70 countries.
-
In October 2025, Thermo Fisher Scientific announced a collaboration with OpenAI, with the AI tools first embedded in its PPD clinical research business to support clinical trial operations.
-
In August 2025, IQVIA and Flagship Pioneering announced a strategic collaboration to apply AI agents and data analytics to clinical development for biotechnology companies.
-
In July 2025, Tigermed completed the acquisition of Micron, a Tokyo-based imaging contract research organization with more than 160 staff, to strengthen its imaging capabilities in Japan and Asia Pacific.
Scope and Research Methodology
The study defines the Functional Service Providers (FSP) Market as clinical research services that sponsors purchase from external providers on a dedicated team or function basis, including clinical monitoring, data management, biostatistics and programming, medical writing, pharmacovigilance, and regulatory affairs. Full-service contract research arrangements, preclinical services, and technology licenses are outside the scope. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are expressed in USD. The segmentation covers service type, development stage, therapeutic area, end user, and region, along with leading countries in each region. Country-level analysis covers the United States, Canada, Germany, the United Kingdom, France, Japan, China, India, Australia, and Brazil.
The evidence base includes provider annual reports, investor materials, regulator and clinical trial registry data, sponsor research and development disclosures, and published studies. Interviews and surveys with clinical operations leaders, procurement heads, and executives at sponsors and providers then test assumptions on contract structures, rates, staffing levels, and technology adoption. Views are weighted by seniority and relevance, and both sponsor and provider viewpoints are included to limit bias across regions and organization sizes. Company claims on headcount and capacity are cross-checked against filings and independent sources before they are used.
Market values are built from provider revenue, headcount, and contract volumes, and they are compared with sponsor spending on research and development and with trial activity. Where the two approaches diverge, inputs are revisited until the gap closes. Projections account for trial volumes, regulatory changes, consolidation, automation, and macroeconomic conditions, and every figure is reviewed for consistency across segments, regions, and years, with country values added to match regional and global totals. Sensitivity checks vary trial volumes, billing rates, and utilization of staff to show how each factor shifts the forecast, and the ranges are documented for client review. All values are stated in USD to remove currency effects.
Functional Service Providers (FSP) Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 17.46 Billion |
| Market Size by 2035 | USD 39.15 Billion |
| CAGR | CAGR of 8.41% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Service Type (Clinical Monitoring, Data Management, Biostatistics and Programming, Medical Writing, Pharmacovigilance and Drug Safety, Regulatory Affairs, and Others) • By Development Stage (Clinical Development and Post-Approval) • By Therapeutic Area (Oncology, Cardiovascular, Central Nervous System, Infectious Diseases, Immunology and Inflammation, and Others) • By End User (Pharmaceutical Companies, Biotechnology Companies, Medical Device Companies, and Academic and Research Institutes) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | IQVIA Holdings Inc., Parexel International Corporation, ICON plc, Syneos Health, Inc., Thermo Fisher Scientific Inc. (PPD Clinical Research), Fortrea Holdings Inc., Labcorp Drug Development (Labcorp Holdings Inc.), Precision for Medicine (Precision Medicine Group), Cytel, Inc., Premier Research Group Limited, Worldwide Clinical Trials, Inc. (including Catalyst Clinical Research), Quanticate International Limited, ProPharma Group Holdings, LLC, Aixial Group (including Cmed), Tigermed Consulting Co., Ltd. (Hangzhou Tigermed) |

Frequently Asked Questions
The market was valued at USD 17.46 Billion in 2025 and is projected to reach USD 39.15 Billion by 2035.
The market is expected to register a CAGR of 8.41% from 2026 to 2035.
North America led the market with a 41.38% share in 2025.
Asia Pacific is expected to grow the fastest, at a CAGR of 10.03% from 2026 to 2035.
Key players include IQVIA, Parexel, ICON, Syneos Health, and Thermo Fisher Scientific through PPD.
