
Email Security Market Report Scope & Overview:
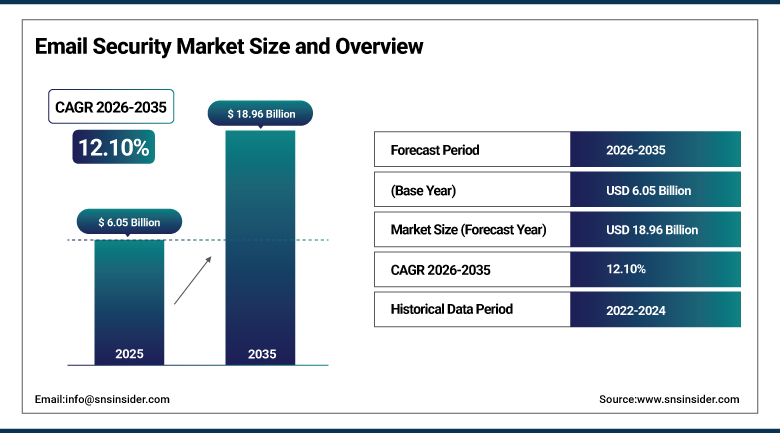
The Email Security Market was valued at USD 6.05 Billion in 2025 and is expected to reach USD 18.96 Billion by 2035, growing at a CAGR of 12.10% from 2026-2035.
The Email Security Market covers the software, appliances and services that protect organizational email from phishing, business email compromise, malware, spam, data leakage and account takeover. As email remains the main entry point for cyberattacks, organizations are layering secure email gateways, API-based cloud protection, encryption, archiving and user awareness training on top of native protections from Microsoft 365 and Google Workspace. Growth is supported by AI-assisted phishing, regulatory pressure on data protection, the shift of mailboxes to the cloud and the spread of remote work, while cost and complexity limit adoption among smaller firms.
⮞Vendors are extending protection to AI agent traffic. In March 2026, Proofpoint announced encryption for interactions between users and AI agents and plans to combine API-based protection with its Secure Email Gateway. The announcement shows how leading providers are widening email security to cover new channels and automated assistants as attackers adopt generative AI.
To Get more information Email Security Market - Request Free Sample Report
Email Security Market Trends
- Shift from perimeter gateways to API-based and cloud-native protection layered on Microsoft 365 and Google Workspace
- Use of machine learning and generative AI to detect socially engineered and AI-written phishing
- Convergence of email protection with security awareness training and human-risk management
- Growing demand for encryption and data loss prevention to meet privacy regulation
- Extension of protection to collaboration tools, browsers and AI assistants
- Consolidation of vendors into broader security platforms
U.S. Email Security Market Outlook
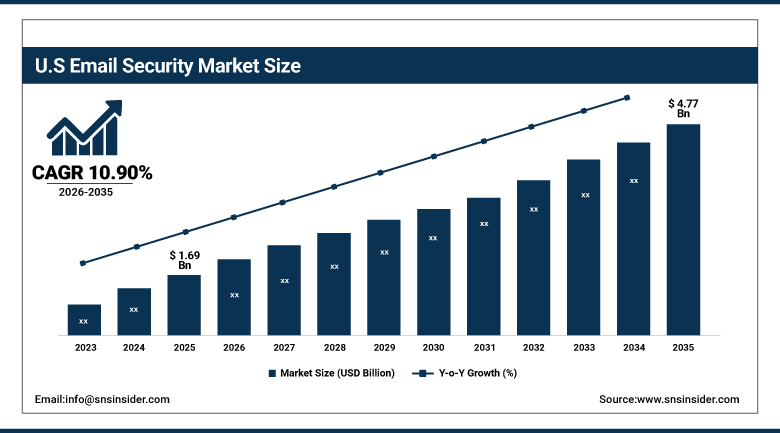
The U.S. Email Security Market was valued at USD 1.69 Billion in 2025 and is expected to reach USD 4.77 Billion by 2035, growing at a CAGR of 10.90% from 2026-2035.
The U.S. Email Security Market is backed by the largest number of cloud mailboxes, high susceptibility to phishing attacks and BEC, regulations governing the financial and healthcare sectors, and the availability of key vendors. Guidelines on email authentication by the government and state breach notification laws encourage companies to increase their controls, while cyber insurance policies now demand email security as an insurance criterion. Growth is moderated by market maturity and by the bundling of basic protections into productivity suites.
⮞Cloud email providers are being supported by third-party security. In July 2025, Broadcom extended Symantec Email Security cloud support to hosted providers such as Zoho, GoDaddy, Amazon SES and IONOS. The move shows how U.S. vendors are widening coverage beyond the largest suites to reach smaller organizations that use hosted mail services.
Email Security Market Segment Analysis
- By Component, solutions segment dominated the Email Security Market in 2025 with 76.40% share; services segment is the fastest-growing segment, with an estimated CAGR of 14.20% during 2026–2035.
- By Deployment, cloud segment dominated the Email Security Market in 2025 with 78.60% share, and is also the fastest-growing segment, with an estimated CAGR of 13.30% during 2026–2035.
- By Organization Size, large enterprises segment dominated the Email Security Market in 2025 with 70.30% share; small and medium enterprises segment is the fastest-growing segment, with an estimated CAGR of 14.50% during 2026–2035.
- By Security Type, secure email gateway segment dominated the Email Security Market in 2025 with an estimated 34.70% share; email encryption segment is the fastest-growing segment, with an estimated CAGR of 15.20% during 2026–2035.
- By End User, BFSI segment dominated the Email Security Market in 2025 with an estimated 35.50% share; IT and telecom segment is the fastest-growing segment, with an estimated CAGR of 13.60% during 2026–2035.
By Component, Solutions Dominate Email Security Market; Services to Register Fastest Growth.
Solutions dominate the Email Security Market because organizations buy gateways, anti-phishing engines, encryption, archiving and data loss prevention products as the core of their defense, and these are licensed per user or per mailbox on recurring subscriptions. Vendors continue to add detection capabilities, such as machine learning for impersonation and attachment sandboxing, which keeps customers renewing and upgrading. Large enterprises standardize on a few suites, which concentrates spending in software. Bundled licensing and enterprise agreements across several modules also encourage customers to consolidate spending with one provider.
Services are projected to register the fastest growth because many organizations lack the staff to tune policies, monitor alerts and respond to targeted attacks. Managed detection, incident response, phishing simulation and security awareness programs are being bundled with software, and professional services help firms migrate from legacy gateways to cloud-based protection. Small and mid-sized companies in particular rely on service providers to deliver continuous monitoring without building internal teams. Demand for fast incident response in particular continues to rise. Specialists offering round-the-clock monitoring are gaining attention.
By Deployment, Cloud Dominates Email Security Market and Is Also the Fastest-Growing Deployment Mode.
Cloud deployment dominates the Email Security Market because most organizations have moved their mailboxes to Microsoft 365 and Google Workspace, and cloud-delivered security integrates naturally with those platforms. Cloud services reduce hardware cost, update threat intelligence continuously and scale quickly across remote workers. API-based products can be deployed within minutes without changing mail routing, which makes adoption faster and attracts organizations that previously avoided gateway projects. Cloud providers also offer built-in reporting and automatic updates that lower the maintenance burden for lean IT teams.
Cloud is also expected to be the fastest-growing deployment mode as vendors retire or de-emphasize appliance products and as regulated industries gain confidence in cloud controls. On-premises deployments persist in government, defense and some financial institutions that keep mail servers in-house, and vendors such as Barracuda continue to refresh appliances for them. Hybrid models bridge the two, combining local control with cloud threat intelligence for organizations that are transitioning gradually. Pay-as-you-go pricing and fast onboarding make cloud services attractive for organizations that need to scale quickly.
By Organization Size, Large Enterprises Dominate Email Security Market; Small and Medium Enterprises to Register Fastest Growth.
Large enterprises dominate the Email Security Market because they hold the greatest number of mailboxes, face the most targeted attacks and operate under strict compliance obligations. They typically buy multiple layers, including gateways, API-based detection, encryption, archiving and training, and they are able to fund dedicated security operations teams. Their purchasing power and multi-year contracts give leading vendors a stable base of revenue. Procurement committees in large organizations demand proof of detection accuracy and integration with existing tools, which favors established brands.
Small and medium enterprises are projected to register the fastest growth as attackers increasingly target them with phishing and invoice fraud, and as cyber insurers require basic controls. Vendors are introducing simpler, lower-priced bundles and partner-led managed offerings that suit organizations without security staff. Awareness remains limited and budgets are tight, but regulation and insurance requirements are pushing these firms from native protections toward dedicated email security. Resellers and managed service providers give these firms access to support at predictable monthly cost, widening the adoption base.
By Security Type, Secure Email Gateway Dominates Email Security Market; Email Encryption to Register Fastest Growth.
Secure email gateways dominate the Email Security Market because they filter spam, malware and phishing before messages reach users and are well established in enterprise architectures. Vendors such as Cisco, Proofpoint, Broadcom and Barracuda continue to enhance sandboxing, URL rewriting and attachment analysis. Many organizations keep a gateway as the primary control even when they add API-based tools, since it provides policy enforcement, data loss prevention and consistent logging. Tuning options and reporting provide visibility that auditors and risk teams rely on to demonstrate compliance with internal and external standards.
Email encryption is expected to show the highest growth due to requirements for protecting sensitive information during transmission in compliance with privacy laws and industry regulations, particularly in healthcare and finance. Encryption technology which is transparent to users and based on policies is gaining popularity, while vendors include it into data loss prevention solutions. Other significant segments include anti-phishing, advanced threat protection, and archiving, with behavioral AI detection taking market share from impersonation attacks. Data loss prevention and archiving add compliance value and often sell together with encryption in regulated sectors.
By End User, BFSI Dominates Email Security Market and IT and Telecom to Register Fastest Growth.
BFSI is the major contributor to the Email Security Market, owing to the fact that banks, insurance companies, and capital market firms fall victim to phishing attacks, possess confidential information, and are regulated. They are highly invested in control mechanisms, encryption, archiving for documentation purposes, and training their employees. Large-scale deals with international vendors and ongoing digitalization of finance services will keep up investments. Fraud losses from payment diversion and executive impersonation are especially costly in this sector, which supports sustained budgets. Regulators expect strong controls.
IT and telecom is projected to register the fastest growth because technology companies run large, cloud-based mail environments, manage vast numbers of customer and employee accounts, and are attractive targets for supply chain attacks. Government, healthcare and media also grow as public agencies modernize cybersecurity and hospitals face ransomware that often arrives by email. Retail, education and manufacturing add demand as digital operations expand and data protection rules widen. Public sector programs to modernize cyber defense, and new reporting rules for incidents, are likely to add demand from agencies and healthcare providers as well.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
80.00 |
|
Europe |
United Kingdom |
28.00 |
|
Asia Pacific |
China |
29.00 |
|
Latin America |
Brazil |
45.00 |
|
Middle East & Africa |
GCC Countries |
60.00 |
North America Email Security Market Insights
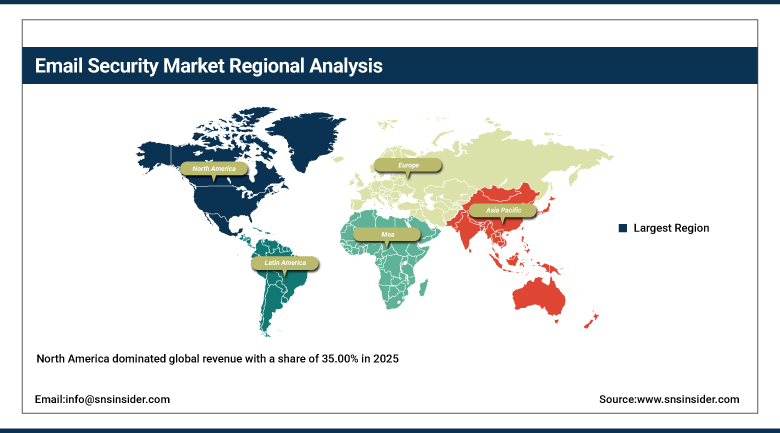
North America dominated global revenue with a share of 35.00% in 2025, supported by the world's largest base of cloud mailboxes, intense phishing activity, strict sector regulation and the presence of vendors such as Cisco, Microsoft, Proofpoint, Broadcom, Barracuda, Mimecast and Fortinet. The United States accounts for the largest share of regional demand, with Canada adding volume. Regional demand is expected to expand at fastest CAGR during 2026-2035. Canada contributes through its banking and public sector, and Mexico is growing as an outsourcing and manufacturing base.
Insurance policies, guidelines issued by the government for authenticating emails, and state privacy laws drive companies to embrace multiple layers of protection. The Broadcom Company improved Symantec Email Security in July 2025 through adding new functionalities to the hosted mail service providers while Barracuda released Secure Email Gateway in January 2026. Costs are increased by artificial intelligence-based phishing; however, maturity and integration within product suites limit the pace of developments. Venture-backed specialists also compete with established vendors, particularly in API-based and behavioral detection, which keeps innovation high across the region. Cyber insurers also push adoption.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Email Security Market Insights
Europe is the second-largest region. The United Kingdom, Germany and France lead, supported by GDPR, the NIS2 directive and national cybersecurity agencies that emphasize email authentication. The region hosts providers such as Sophos, Trend Micro's European operations, Hornetsecurity, Egress and OpenText, and data residency requirements favor vendors with European cloud regions. Nordic and Benelux countries are early adopters of cloud services and email authentication standards, adding to regional demand for modern controls.
Pressure from regulatory requirements for data protection and resiliency spurs spending on encryption, archiving, and incident reporting. Organizations such as banks, government agencies, and health care providers represent major markets, and often prefer sovereignty-based or European-based offerings. In May 2025, OpenText announced a way for Voltage SecureMail Cloud users to migrate to Core Email Encryption. Public sector digitization programs and the need to protect critical infrastructure from phishing and ransomware sustain spending even during periods of cost pressure. Auditors scrutinize results.
Asia Pacific Email Security Market Insights
Asia Pacific is projected to be the fastest-growing region, advancing at a CAGR of 14.00% from 2026-2035. China, India, Japan, Australia and South Korea lead demand, driven by rapid cloud adoption, expanding digital banking and a growing number of targeted attacks on enterprises and governments. Local vendors compete with global providers and tailor products to language and data localization needs. Southeast Asian economies including Singapore, Indonesia and Vietnam are adding demand through digital banking and e-commerce growth. Government agencies also expand programs.
Growing adoption of mobile and cloud computing by small- to medium-size companies results in an addressable market, while data protection and breach disclosure laws are being tightened by authorities in Japan, Singapore, Australia and India. In June 2025, Fortinet introduced a new AI-enabled FortiMail Workspace Security solution that includes email, browser and collaboration security, while global providers are forging distribution alliances. Local telecom operators and managed security providers resell protection to small businesses, which accelerates adoption outside large cities.
MEA & Latin America Email Security Market Insights
In Latin America, Brazil leads on the strength of its large financial sector and widespread phishing activity, followed by Mexico, Argentina and Colombia. Regional demand growth is supported by cloud migration, new data protection laws and banking digitization. Local resellers and managed service providers play a central role in reaching mid-sized organizations. Chile and Peru also add demand through banking and mining groups that have strengthened cyber programs. Rising smartphone use and online banking across the region also expose more users to phishing, which keeps security budgets growing steadily.
For the Middle East and Africa, the Gulf Cooperation Council (GCC) countries take the lead through their national cybersecurity strategy and digital government initiatives, while South Africa, Turkey, and Egypt follow. The region’s growth is enabled through significant investments into smart cities and fintech projects. Lack of skills and awareness hinders adoption of technology, making managed and cloud offerings particularly appealing. Egypt and Nigeria add momentum through fintech expansion, while Saudi Arabia and the UAE invest in national cybersecurity centers and mandate protective controls in critical sectors.
Market Dynamics
Growth Drivers: Phishing Sophistication, Cloud Email and Regulation
The rising volume and sophistication of phishing and business email compromise is the main driver of the Email Security Market. Generative AI lets attackers write convincing messages in many languages with no spelling errors, and impersonation of executives and suppliers causes large financial losses. Native filters in cloud mailboxes catch bulk threats but miss targeted attacks, so organizations add specialized layers that analyze behavior and context. Investments by governments in national cyber readiness add to demand in public sector and critical infrastructure mailboxes.
Cloud migration and remote work have increased the number of mailboxes outside traditional perimeters, while regulation such as GDPR, HIPAA and sector-specific rules mandate protection of sensitive data. Cyber insurance underwriters now ask for email security controls, bringing smaller firms into the market, and security awareness training demand grows alongside technical products. Higher awareness at board level of the cost of breaches also supports budgets.
Restraints: Cost, Complexity and Native Platform Bundling
High deployment cost and complexity restrain adoption among small organizations that lack security staff. Tuning policies, managing false positives and integrating with identity and endpoint tools demand skills that many firms do not have, and licensing is often priced per user, which adds up quickly. Alert fatigue from false positives can also lead teams to loosen policies, reducing the value of expensive tools.
Microsoft and Google continue to improve native protections and bundle advanced features into premium licenses, which can lead customers to question the need for third-party products. Vendor consolidation and aggressive pricing also compress margins for point-solution providers and make differentiation harder. Concerns about privacy and data residency when scanning message content in the cloud can also slow adoption in some regions and sectors.
Opportunities: AI Detection, Human-Risk Management and Managed Services
Detecting attacks using AI that looks at writing style and behavioral relationships is a solution to thwart attacks that are not picked up by signatures, and vendors who can demonstrate accurate detection with minimal false positives will get displacement contracts. The combination of email security protection along with security awareness training through additions such as Sophos' Phish Threat in November 2025 helps increase their human risk portfolio.
Services and partner-bundled solutions unlock the SMB market, whereas protection of collaboration apps, browsers, and AI assistants increases the total addressable market. Providers with unified suites offering clear-cut pricing will win over more budgets as customers reduce their vendors. The increasing need for protection of messaging within AI assistants and chat apps can increase the market for providers having a good classification capability for data.
Recent Developments:
- 2026: Barracuda launched a next-generation Secure Email Gateway with stronger sandboxing and automated malware detonation. The release targets advanced attachments and links that bypass basic filters.
- 2026: Mimecast introduced full-stack email threat detection through API deployment, bringing URL inspection, malware sandboxing, behavioral AI, and business email compromise protection to cloud email environments.
- 2026: Cisco announced Remote Browser Isolation and Content Disarm and Reconstruction enhancements for Secure Email Gateway, helping isolate risky links and sanitize potentially dangerous attachments.
- 2025: Sophos added Phish Threat, which combines email protection with user awareness training. The addition gives customers phishing simulation and protection in a single platform.
Email Security Market Key Players are:
- Cisco Systems, Inc.
- Microsoft Corporation
- Google LLC
- Broadcom Inc. (Symantec)
- Proofpoint, Inc.
- Mimecast Limited
- Barracuda Networks, Inc.
- Trend Micro Incorporated
- Check Point Software Technologies Ltd.
- Sophos Ltd.
- Fortinet, Inc.
- OpenText Corporation
- Forcepoint LLC
- Abnormal Security
- Darktrace plc
- Egress Software Technologies
- Palo Alto Networks, Inc.
- Hornetsecurity GmbH
- TitanHQ
- IBM Corporation
Email Security Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.05 Billion |
| Market Size by 2035 | USD 18.96 Billion |
| CAGR | CAGR of 12.10% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Solutions, Services) • By Deployment (Cloud, On-Premises, Hybrid) • By Organization Size (Large Enterprises, Small and Medium Enterprises) • By Security Type (Secure Email Gateway, Email Encryption, Anti-Phishing and Advanced Threat Protection, Data Loss Prevention, Archiving, Others) • By End User (BFSI, IT and Telecom, Government, Healthcare, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Cisco Systems, Inc., Microsoft Corporation, Google LLC, Broadcom Inc. (Symantec), Proofpoint, Inc., Mimecast Limited, Barracuda Networks, Inc., Trend Micro Incorporated, Check Point Software Technologies Ltd., Sophos Ltd., Fortinet, Inc., OpenText Corporation, Forcepoint LLC, Abnormal Security, Darktrace plc, Egress Software Technologies, Palo Alto Networks, Inc., Hornetsecurity GmbH, TitanHQ, IBM Corporation |

Frequently Asked Questions
Key players include Cisco Systems, Inc., Microsoft Corporation, Google LLC, Broadcom Inc., Proofpoint, Inc., Mimecast Limited, Barracuda Networks, Inc., Trend Micro Incorporated and Check Point Software Technologies Ltd.
Key opportunities include AI-based detection, human-risk management, managed services for small firms, and expansion of protection to collaboration tools and AI assistants.
The major growth factor is the rising sophistication of phishing and business email compromise, amplified by generative AI and cloud mailbox adoption.
By Component, the Solutions segment dominated the market in 2025 with a 76.40% share, supported by recurring subscriptions for gateways, anti-phishing and encryption products.
North America dominated the market with a share of 35.00% in 2025, driven by cloud mailbox adoption, phishing exposure and strong regulation.
