
Elderly Walker Market Report Scope & Overview:
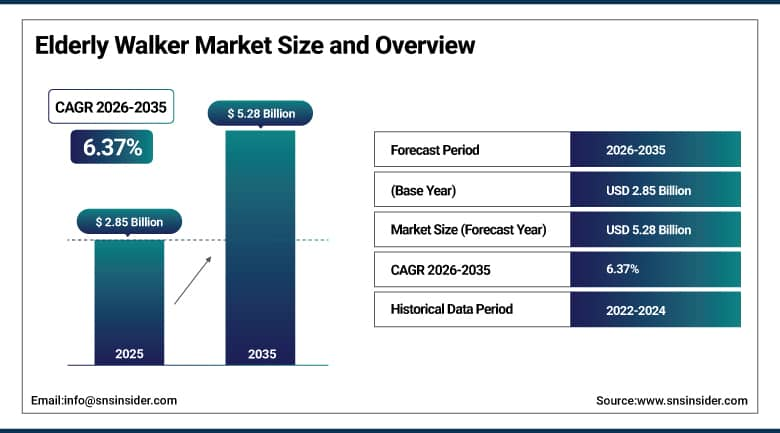
The Elderly Walker Market was valued at USD 2.85 Billion in 2025 and is expected to reach USD 5.28 Billion by 2035, growing at a CAGR of 6.37% from 2026-2035.
The Elderly Walker Market is expanding as populations age, falls prevention becomes a health priority and more older adults choose to stay in their own homes. Rollators, wheeled walkers, standard frames and knee walkers help seniors and post-surgical patients keep their balance and stay active. Manufacturers are adding lighter aluminum and carbon fiber frames, folding designs, seats, brakes and sensors that track activity and tip-overs. Reimbursement rules, caregiver needs and online retail are changing how products reach users. Producers in Europe and Asia compete on design, while large North American brands compete on distribution reach.
⮞In October 2025, the World Health Organization noted that one in six people worldwide will be aged 60 years or over by 2030. The demographic shift supports steady long-term demand for mobility aids.
To Get More Information On Elderly Walker Market - Request Free Sample Report
Elderly Walker Market Trends:
-
Lightweight aluminum and carbon fiber rollators with folding frames
-
Smart walkers with sensors that track activity, falls and tip-overs
-
Growth of online sales and direct-to-consumer mobility brands
-
Aging-in-place programs shifting use from hospitals to homes
-
Expansion of knee walkers and rollators for orthopedic recovery
U.S. Elderly Walker Market Outlook:
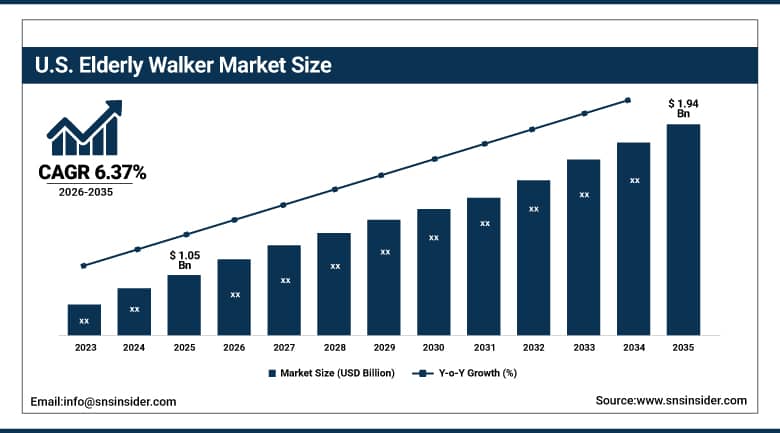
The U.S. Elderly Walker Market was valued at USD 1.05 Billion in 2025 and is expected to reach USD 1.94 Billion by 2035, growing at a CAGR of 6.37% from 2026-2035.
The U.S. Elderly Walker Market is the largest national market in the world, supported by a large population of adults aged 65 and over, strong Medicare coverage of durable medical equipment and a mature retail network. Rollators lead purchases, with pharmacies, medical supply stores and online platforms serving a wide range of buyers. Falls prevention programs, hospital discharge planning and a preference for aging at home sustain demand. Import tariffs and fee schedule updates affect pricing. Brands are adding smart features and lighter frames to stand out.
⮞In June 2026, the U.S. Census Bureau reported 64.6 million residents aged 65 and over as of July 2025, up 16.2% since April 2020. The expanding senior population underpins steady purchases of walkers and rollators.
Elderly Walker Market Segment Analysis:
-
By Product Type, the Rollators segment dominated the Elderly Walker Market with approximately 55.80% share in 2025, while the Knee Walkers segment is the fastest growing with a CAGR of approximately 6.92%.
-
By Application, the Geriatric Care segment dominated the Elderly Walker Market with approximately 47.70% share in 2025, while the Emergency Care segment is the fastest growing with a CAGR of approximately 7.07%.
-
By End Use, the Homecare segment dominated the Elderly Walker Market with approximately 43.08% share in 2025, while the Rehabilitation Centers segment is the fastest growing with a CAGR of approximately 7.17%.
-
By Distribution Channel, the Offline segment dominated the Elderly Walker Market with approximately 63.25% share in 2025, while the Online segment is the fastest growing with a CAGR of approximately 6.97%.
By Product Type, Rollators Dominate the Elderly Walker Market and Knee Walkers Grow Fastest
Rollators lead because their wheels, hand brakes, seats and storage baskets suit seniors who still walk outdoors but tire easily. Four-wheel models give stability on pavement, while three-wheel versions fit narrow hallways. Lightweight aluminum frames and folding designs have widened appeal, and rollators are widely stocked by pharmacies and medical suppliers. Insurance coverage in several countries also supports purchases.
Knee walkers are the fastest growing as patients recovering from foot, ankle and lower-leg surgery prefer them to crutches. The design lets users rest the injured leg on a padded platform and propel themselves with the healthy leg, which reduces strain on hands and shoulders. Rental programs, orthopedic clinics and online retailers are broadening access, and younger patients are adding to the older user base.
⮞In January 2026, the Centers for Medicare & Medicaid Services applied a 2.0% net update to the durable medical equipment fee schedule for the calendar year. The adjustment shapes reimbursement for walkers and rollators supplied to Medicare beneficiaries.
By Application, Geriatric Care Dominates the Elderly Walker Market and Emergency Care Grows Fastest
Geriatrics is the market leader application due to most of the walkers being purchased by elderly customers who suffer from balance problems, arthritis, low muscle strength or chronic illnesses. The physicians and physical therapists prescribe walkers to help reduce the risks of falls and remain independent. Nursing homes and agencies providing home health services procure walkers in bulk. The aging populations in Japan, Europe and North America have made this particular application the leader among all others.
The application experiencing rapid growth in the last couple of years is the emergency care sector where the hospitals and urgent care facilities are sending more patients back home after fracturing bones, suffering from sprains or undergoing surgeries. Walker is supplied when the patient is discharged so that he or she can walk around safely until further medical attention.
⮞In September 2025, the National Hip Fracture Database in the United Kingdom reported about 76,000 hip fractures a year. The volume of fractures drives frequent need for post-injury walking aids.
By End Use, Homecare Dominates the Elderly Walker Market and Rehabilitation Centers Grow Fastest
Homecare leads because most older adults want to remain in their own homes and buy walkers directly or through home health suppliers. Caregivers favor lightweight and foldable models that fit small apartments and car trunks. Remote monitoring and home modification programs are encouraging use of safe mobility aids. Families also purchase second units for travel and for use in different rooms.
Rehabilitation centers are the fastest growing end use as stroke, orthopedic and neurological patients enter structured therapy programs. Therapists use rollators, gait trainers and standard walkers to rebuild strength and confidence, and clinics are replacing aging fleets with adjustable and sensor-equipped devices. Rising numbers of joint replacement and fracture surgeries are lifting referrals to outpatient rehabilitation.
⮞In March 2025, AARP reported that 75% of adults aged 50 and over want to stay in their homes for the long term. The preference supports demand for mobility aids used at home.
By Distribution Channel, Offline Dominates the Elderly Walker Market and Online Grows Fastest
Offline sales come first as consumers seek to test the adjustment of height, braking, and weight before buying. Pharmacists, medical equipment shop assistants, and therapists give guidance on fit as well. Walkers are provided by hospitals and clinics on patient discharge as well. Insurances are processed via the physical sellers in many countries, and this keeps them relevant. Specialist shops build credibility through offering repairs and renting.
The online channel is experiencing the most growth due to model comparisons, reviews, and ordering to have the product delivered. Online brands offer lightweight and fashion rollators on their websites and marketplaces, and also subscription services related to accessories. Adult children in the younger generations are the ones making purchases for their parents. The barrier of online purchases is being made easier through better returns and video guides.
⮞In September 2026, the UK Office for National Statistics reported that internet sales made up 27.3% of total retail sales in August. The share shows the growing comfort of consumers with buying online.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
95.43 |
|
Europe |
Germany |
22.94 |
|
Asia Pacific |
China |
33.71 |
|
Latin America |
Brazil |
44.62 |
|
Middle East & Africa |
Saudi Arabia |
18.37 |
North America Elderly Walker Market Insights
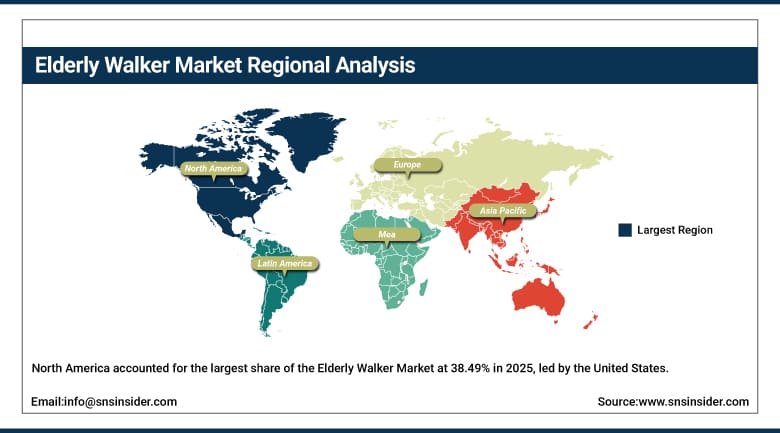
North America accounted for the largest share of the Elderly Walker Market at 38.49% in 2025, led by the United States. A large population of older adults, broad insurance coverage for durable medical equipment and a dense network of pharmacies and medical suppliers sustain demand. Canada adds steady volumes through provincial assistive device programs, and leading brands maintain strong distribution across the region.
Product innovation is active. Manufacturers are launching lighter frames, sensor-equipped walkers and fall detection add-ons, and online retail is growing rapidly. Tariff exposure on imported components and cost pressure from reimbursement schedules affect pricing. Falls prevention initiatives by health agencies and employers of caregivers continue to bring attention to safe mobility.
⮞In September 2025, Statistics Canada reported 8.1 million Canadians aged 65 and over, or 19.5% of the population, as of July 2025. The older population is growing faster than any other age group.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Elderly Walker Market Insights
Europe is led by Germany, the United Kingdom, France, Italy and the Nordic countries. Design-oriented rollator makers in Sweden, Norway and the Netherlands are well known, and public health systems often supply mobility aids through assessment programs. Demand is stable because of the region's high share of older residents.
In Germany and the Nordic region, customers prefer lightweight and fashionable models, whereas southern Europe is seeing more purchasing via retail and Internet sales. Tender procedures have an effect on pricing in a number of nations. Recent mergers among the mobility firms have changed the supplier mix, and Europeans have a keen interest in ergonomic and safe products.
⮞In early 2026, Eurostat reported that 22.0% of the European Union population was aged 65 or over in January 2025, and 6.2% was aged 80 or over. The age profile points to continued need for walking aids.
Asia Pacific Elderly Walker Market Insights
Asia Pacific held about 18.48% of the Elderly Walker Market in 2025 and is projected to be the fastest growing region, with a CAGR of 7.42% over 2026-2035. Japan, China, South Korea, Australia and India lead. Japan has the oldest population among large economies, and China's elderly population is expanding rapidly, which creates large future demand.
Increased earnings and government elder care services are motivating more purchases. The long-term care insurance in Japan facilitates the rental of mobility equipment, and Chinese firms are increasing exports and domestic sales of rollators. Online channels help in reaching rural customers. Cost sensitivity continues to be an issue, and hence local manufacturers offer aluminum mobility aid equipment, which is relatively cheaper than global brands.
⮞In July 2026, China's Ministry of Civil Affairs reported 323.38 million people aged 60 and over at the end of 2025, or 23% of the population. The scale of the aging population is driving eldercare investment.
MEA & Latin America Elderly Walker Market Insights
Latin America and the Middle East and Africa together hold about 16.10% of the Elderly Walker Market. In Latin America, Brazil, Mexico, Argentina and Chile lead as populations age quickly and private insurance expands. Most products are imported from Asia and North America, and pharmacies and orthopedic stores are the main outlets.
The leading markets for such products in the Middle East and Africa are Gulf States and South Africa due to development in private health care, rehabilitation centers and health tourism. Populations of elderly people are small yet growing in Egypt, Turkey and Saudi Arabia. Absence of state support for mobility equipment reduces volume, while reliance on imports makes prices vulnerable to exchange rates.
⮞In June 2025, the Economic Commission for Latin America and the Caribbean noted that about 98 million people in the region are aged 60 and over, rising to 183 million by 2050. The projection shows long-term demand for mobility aids.
Market Dynamics:
Growth Drivers: Population Aging and Falls Prevention Drive Growth in the Elderly Walker Market
Population aging is the central driver. Older adults experience reduced balance, muscle loss, joint disease and neurological conditions, and walkers are the most common assistive device for maintaining mobility. Health systems recognize that preventing one hip fracture saves substantial care costs, so physicians and therapists recommend walkers early. Growth in the population aged 80 and over is especially important.
Technology and care models add momentum. Lightweight alloys, carbon fiber and improved braking make walkers easier to use, while sensors and apps give caregivers visibility into activity. Aging-in-place policies shift care from facilities to homes, increasing direct purchases. Wider insurance coverage and growing online availability make it easier for families to obtain suitable devices.
⮞In September 2026, the U.S. Centers for Disease Control and Prevention reported that the age-adjusted fall death rate among older adults rose 21%, from 64.7 per 100,000 in 2018 to 78.4 per 100,000 in 2024. The trend increases pressure on falls prevention.
Restraints: Cost Pressure and Trade Uncertainty Restrain Growth in the Elderly Walker Market
Cost considerations hinder growth. Older persons are usually on fixed income and reimbursement for walkers is low or outdated in some countries. Walkers made with premium carbon fiber and equipped with sensors are not affordable by many people. Walkers that are imported from foreign countries are relatively cheap and reduce profit margins.
The issue of trade hinders the growth of the industry further. Walkers and their components are manufactured in Asian countries and exported to Western markets, hence increased cost due to tariffs and logistics costs. Compliance cost arises due to the need to meet the safety standards for the products. There is also a tendency among users to reject walkers due to stigma.
⮞In September 2025, the U.S. Department of Commerce opened a Section 232 national security investigation into imports of medical equipment and devices, with wheelchairs and hospital beds among the products named. The inquiry creates tariff risk for imported mobility aids.
Opportunities: Smart Walkers and Fast-Aging Asian Markets Create Opportunities in the Elderly Walker Market
There is great potential for smart walkers. Step counters, fall detectors, nighttime activity monitors and caregivers alerts instill trust among family members and allow senior living facilities to manage risks. Subscription models will generate revenue through monthly subscriptions for suppliers while gait analytics could be used in clinical settings. Companies which develop robust hardware with easy-to-use apps will develop a strong customer base.
There is great potential in rapidly aging Asian countries. In countries such as Japan, China and South Korea, governments have developed eldercare services as well as long-term care insurance schemes where assistive devices are included in the package. These countries are good for local manufacturing, rentals as well as e-commerce of such products.
⮞In September 2026, Japan's Ministry of Internal Affairs and Communications reported that people aged 65 and over reached a record 29.6% of the population, about 36.24 million. The figure is the highest among countries with populations above 40 million.
Recent Developments:
-
In March 2026, Drive DeVilbiss Healthcare launched WalkWise, a battery-powered activity monitor that attaches to the front wheel of a walker or rollator. The device tracks inactivity, tip-overs and night-time use and sends alerts to caregivers through a subscription app.
-
In June 2026, DHCare, formed from Invacare Europe and Direct Healthcare Group, signed an agreement to acquire Ottobock's Human Mobility division. The deal adds complex mobility products and strengthens DHCare's position in the German-speaking markets, with closing expected in the second half of 2026.
-
In December 2025, Rollz International announced that its UK arm would take over distribution of TOPRO rollators and walking aids from January 2026. The arrangement covers orders, delivery, servicing, warranty and spare parts for UK customers.
-
In April 2026, Rehasense launched its Driver all-terrain rollator and the Starlight and Starlight Plus carbon fiber rollators at Naidex. The all-terrain model carries users up to 200 kilograms, and the carbon models add a floating frame and anti-tip weights.
Elderly Walker Market Key Players are:
-
Drive DeVilbiss Healthcare
-
Carex Health Brands
-
Medline Industries, LP
-
Sunrise Medical
-
Stander Inc.
-
Human Care Group
-
TOPRO Mobility
-
Karman Healthcare, Inc.
-
Trionic (Veloped)
-
Rollz International
-
Rehasense
-
MEYRA GmbH
-
Journey Health & Lifestyle
-
Mobilex A/S
-
Invacare (DHCare)
Elderly Walker Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.85 Billion |
| Market Size by 2035 | USD 5.28 Billion |
| CAGR | CAGR of 6.37% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Rollators, Wheeled Walkers, Standard Walkers, Knee Walkers, and Others) • By Application (Geriatric Care, Orthopedic Care, Emergency Care, and Others) • By End Use (Homecare, Hospitals and Clinics, Rehabilitation Centers, and Elderly Care Facilities) • By Distribution Channel (Offline and Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Drive DeVilbiss Healthcare, Carex Health Brands, Medline Industries, LP, Sunrise Medical, Stander Inc., Human Care Group, TOPRO Mobility, Karman Healthcare, Inc., Trionic (Veloped), Rollz International, Rehasense, MEYRA GmbH, Journey Health & Lifestyle, Mobilex A/S, Invacare (DHCare) |

Frequently Asked Questions
Key players include Drive DeVilbiss Healthcare, Carex Health Brands, Medline, Sunrise Medical, Stander, Human Care Group, TOPRO Mobility, Karman Healthcare, Trionic, Rollz International, Rehasense, MEYRA, Journey Health & Lifestyle, Mobilex and Invacare (DHCare).
Key opportunities include smart walkers with fall and activity sensors, subscription monitoring services, lightweight carbon fiber designs and fast-aging Asian markets.
Population aging and the focus on falls prevention are the main growth factors, supported by aging-in-place policies and wider insurance coverage.
By Product Type, the Rollators segment dominated the market in 2025 with an estimated 55.80% share, supported by stability, brakes, seats and storage.
North America dominated the market with a share of 38.49% in 2025, driven by a large older population, broad insurance coverage and dense retail networks.
