
Thermal Barrier Coatings Market Report Scope & Overview:
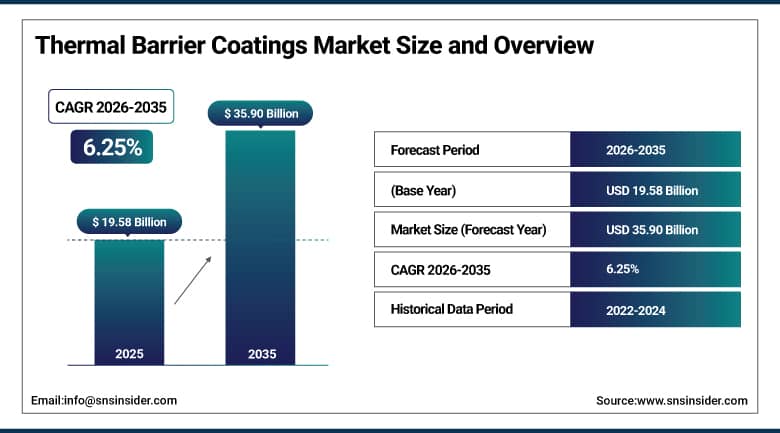
The Thermal Barrier Coatings Market was valued at USD 19.58 Billion in 2025 and is expected to reach USD 35.90 Billion by 2035, growing at a CAGR of 6.25% from 2026-2035.
The Thermal Barrier Coatings Market is expanding as turbine and engine makers push operating temperatures higher to cut fuel burn and emissions. Ceramic top coats keep nickel superalloy parts below their failure point, which extends component life and trims maintenance cost. Aerospace remains the largest user, while gas-fired power plants and high-performance vehicles add steady volume. Asia Pacific leads on aircraft assembly growth and large power build-outs. Rare-earth zirconates are widening the materials base. Yttrium supply risk is reshaping sourcing choices. Repair and overhaul work adds recurring demand as blades and vanes are recoated several times during an engine life, which stabilizes revenue for coating providers.
⮞The International Air Transport Association reported in January 2026 that global passenger demand, measured in revenue passenger kilometers, grew 5.7% year on year in November 2025. Sustained traffic growth keeps engine fleets flying and shortens the interval between hot-section repairs, both of which draw on thermal barrier coating capacity.
To Get More Information On Thermal Barrier Coatings Market - Request Free Sample Report
Thermal Barrier Coatings Market Trends
-
Operators are shifting from standard YSZ toward rare-earth zirconates, high-entropy oxides and CMAS-resistant top coats.
-
Suspension plasma spray is emerging as a columnar alternative to EB-PVD while new EB-PVD repair capacity enters service.
-
Yttrium export controls introduced in April 2025 are pushing coaters toward stock management and substitute research.
-
Gas turbine and aero engine build-outs are pulling coating volume and widening approved repair capacity.
-
Automated thermal spray cells and equipment consolidation are improving repeatability across production and repair lines.
U.S. Thermal Barrier Coatings Market Outlook
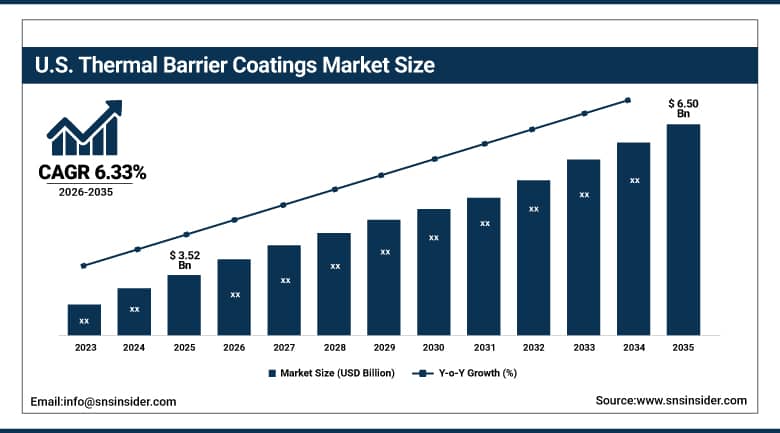
The U.S. Thermal Barrier Coatings Market was valued at USD 3.52 Billion in 2025 and is projected to reach USD 6.50 Billion by 2035, growing at a CAGR of 6.33% from 2026-2035.
The U.S. Thermal Barrier Coatings Market benefits from a large installed base of aero engines and heavy-duty gas turbines. Engine makers, military programs and business aviation all specify coated hot sections. Overhaul shops recoat blades and vanes on a regular cycle. Gas-fired generation adds new combined cycle and peaking units each year. Federal research funding supports advanced ceramics for higher inlet temperatures and new engine concepts. Supply of yttrium and zirconia feedstock is a growing concern for coaters. Even so the country remains the center of technology development and approved repair work in North America. Qualified local capacity remains scarce relative to fleet needs.
⮞In February 2026, the U.S. Energy Information Administration reported that developers plan to add 6.3 GW of gas-fired generating capacity in 2026, spanning combined cycle plants and combustion turbines. Each of those machines relies on coated combustor and turbine parts, which supports new-build coating demand.
Thermal Barrier Coatings Market Segment Analysis
-
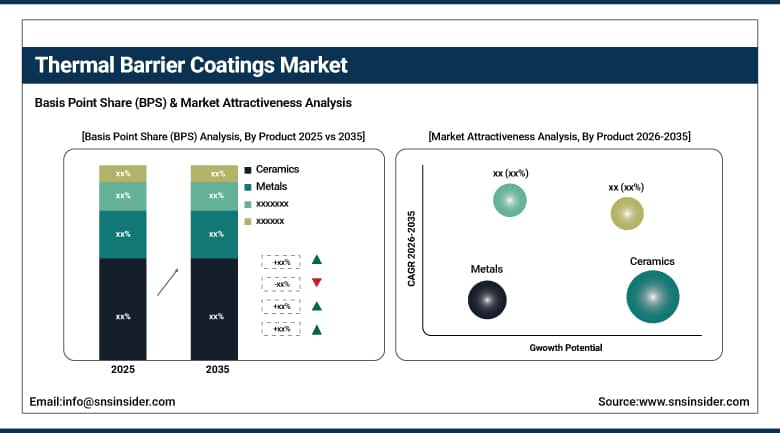
By Product, the Ceramics segment dominated the Thermal Barrier Coatings Market in 2025 with an estimated 34.50% share, while Metals are projected to register the fastest growth at a CAGR of approximately 7.20%.
-
By Application, the Aerospace segment dominated the Thermal Barrier Coatings Market in 2025 with an estimated 30.00% share, while Stationary Power Plants are expected to grow at a CAGR of approximately 8.60%.
-
By Technology, the Plasma Spray segment held a leading position in the Thermal Barrier Coatings Market in 2025, while Flame Spray is anticipated to register the fastest growth at a CAGR of approximately 7.56%.
-
By Coating Material, Ceramic Yttria-Stabilized Zirconia (YSZ) dominated the Thermal Barrier Coatings Market in 2025 and is projected to expand at a CAGR of approximately 7.59%.
By Product, Ceramic Dominates the Thermal Barrier Coatings Market and Metal Grows Fastest
The Ceramics segment dominated the Thermal Barrier Coatings Market in 2025, it can be attributed to their excellent heat insulation capacity, high-temperature stability, and resistance to oxidation and corrosion. Ceramic coatings help in protecting metal parts from high temperatures and thermal cycling. The usage of ceramics in gas turbines, airplane engines, and industrial power generation systems helps in boosting their demand. Further enhancements in the coating deposition process, durability, and thermal resistance capabilities help in reinforcing the position of this segment in the high-temperature industry.
The Metals segment is projected to register the fastest growth at an estimated CAGR of 5.20%, owing to the rise in the demand for metallic coatings and bond coats. These metallic coatings offer oxidation resistance, corrosion resistance, and thermal expansion capabilities of the metallic layers. The usage of metallic materials in the multi-layer coating system will help in extending the life cycle of the component. Further developments in the coating formulation and coating process will help in increasing their acceptance in aerospace
⮞GE Aerospace reported in January 2026 that it delivered 2,386 commercial engines during 2025. The blades and vanes in each engine carry a ceramic top coat over a metallic bond coat, which sustains demand for both product groups.
By Application, Aerospace Dominates Thermal Barrier Coatings Market; Stationary Power Plants to Register Fastest Growth.
The Aerospace segment dominated the Thermal Barrier Coatings Market in 2025, with an estimated 30.00% share, due to the requirement for protection of turbine blades, combustors, and other parts of engines that are exposed to high temperatures. The thermal barrier coating helps in achieving higher operating temperatures as well as helps in lowering the temperature of metal substrates. Aircraft engine production and maintenance activities, and improvements in fuel efficiency further add to the demand for the product.
The Stationary Power Plants segment is expected to grow at an estimated CAGR of 5.60%, owing to the increasing investment in gas-fired power generation and modernization of turbine infrastructure. Thermal barrier coatings help in protecting combustion and turbine components from high temperatures. The focus on improving the efficiency of power generation, reliability of equipment, and maintenance costs further drives the adoption of the product. Modernization of existing plants and the use of high-efficiency gas turbines drive the demand for the product.
⮞In January 2026, Airbus reported 793 commercial aircraft deliveries for 2025. Output at that level adds new engine sets each month and widens the base of airframes that will need hot-section recoating in later years.
By Technology, Plasma Spray Leads Thermal Barrier Coatings Market; Flame Spray to Register Fastest Growth.
The Plasma Spray segment held a leading position in the Thermal Barrier Coatings Market in 2025 since it can coat high-melting point ceramics to components that need thermal protection. It provides flexibility in coating thickness, material choice, and substrate coverage and is suitable for turbine blades, combustion chambers, and aerospace engine components. Its established use in industry, significant experience with the process, and compatibility with common ceramic coating materials justify its use. Improved coating control and quality further underscore the importance of plasma spraying in high-temperature applications.
The Flame Spray segment is anticipated to register the fastest growth at an estimated CAGR of 5.30%, due to the relative ease of equipment needed and versatility in industrial coating applications. It is based on the combustion of heat to melt or soften the feed stock material before depositing it on the prepared surface. The possibility of being suitable for selected repair, refurbishment, and coating tasks justifies the use of the process. Demand can be driven by maintenance activities in industries and improved process control, although adoption will depend on the desired coating properties.
By Coating Material, YSZ Dominates Thermal Barrier Coatings Market and Is Projected to Register Strong Growth.
Ceramic Yttria-Stabilized Zirconia (YSZ) dominated the Thermal Barrier Coatings Market in 2025 because of its low thermal conductivity, high-temperature capability, and ability to accommodate thermal stresses. YSZ is widely used as a ceramic topcoat in gas turbine and aerospace engine components, where it helps shield metal substrates from intense heat. Its established performance in thermal protection systems, compatibility with common coating processes, and extensive industrial adoption support its leading position. Continued demand for efficient, durable turbine components sustains the importance of YSZ-based coatings.
The YSZ segment is projected to expand at an estimated CAGR of 5.50%, supported by continued requirements for thermal protection in advanced gas turbines and aircraft engines. Its combination of low thermal conductivity and high-temperature stability makes it suitable for components operating under demanding thermal conditions. Ongoing development of coating architectures and deposition techniques aims to improve durability and resistance to thermal cycling. As power-generation operators and aerospace manufacturers seek improved component performance and longer service intervals, demand for established YSZ-based coating systems is expected to remain strong.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
41.37 |
|
North America |
United States |
69.23 |
|
Europe |
Germany |
28.94 |
|
Latin America |
Brazil |
46.58 |
|
Middle East & Africa |
Saudi Arabia |
34.61 |
Asia Pacific Thermal Barrier Coatings Market Insights
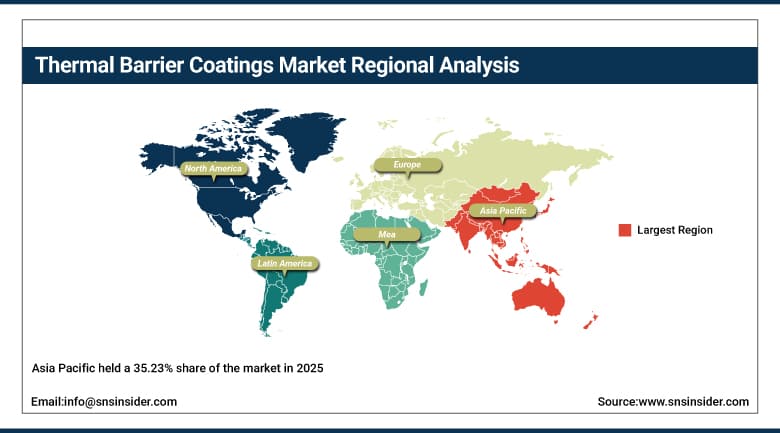
Asia Pacific held a 35.23% share of the market in 2025 and anchors global demand through aircraft assembly growth, large power build-outs and expanding vehicle output. China is adding gas turbine and aero engine capacity at scale. Japan runs a fully integrated aero engine chain, and South Korean shipyards fit LNG dual-fuel engines that depend on coated components. India is opening repair and coating shops as private aerospace investment rises, which lifts the regional base for both new-build and aftermarket work.
Expansion is projected at a CAGR of 7.05% across 2026-2035, the quickest of any region. Local manufacturers are qualifying coaters closer to engine and turbine assembly lines to shorten supply routes, and rising air travel keeps fleet maintenance volumes high. Regional powder producers are offering competitive pricing that widens access for mid-sized shops. Government-backed programs for indigenous engines and power equipment add a further layer of demand over the forecast period. Operators are also seeking shorter turnaround times for recoating.
⮞In January 2026, China's National Energy Administration reported that installed power generating capacity reached about 3.89 billion kW at the end of 2025, up 16.1% year on year. A larger and more flexible power system raises the call on gas turbines for balancing duty, and those machines depend on coated hot sections.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Thermal Barrier Coatings Market Insights
North America accounts for 26.00% of the market, with the United States contributing 69.23% of regional value and Canada supplying the remainder through regional jet and engine programs centered on Montreal. Demand rests on commercial and military engine production, a mature gas turbine fleet and a dense network of approved overhaul facilities. Parts manufacturer approval repairs give independent coaters a route into hot-section work once reserved for engine makers. Defense engine programs and the business jet sector add steady, specification-driven coating volumes.
Investment in coating capacity continues despite tight feedstock conditions. Shops are adding electron beam and plasma spray lines to serve both new and in-service engines, and public research programs are testing garnet-based ceramics for turbine inlet temperatures near 1,700 degrees Celsius. Utilities are also retrofitting older gas turbines with upgraded coatings to improve heat rate. The region therefore combines steady volume demand with leadership in advanced material development. Qualification cycles are long, so suppliers already holding approvals enjoy durable customer relationships.
⮞Boeing reported in January 2026 that it delivered 600 commercial airplanes in 2025, the highest annual total since 2018. A rising build rate lifts demand for coated engine parts across the North American supply base.
Europe Thermal Barrier Coatings Market Insights
Europe holds 25.51% of the market, and its demand centers on aero engine production in Germany, the United Kingdom and France. Germany also runs large turbocharger lines that apply heat management coatings to automotive components. Established engine makers maintain captive coating centers, while independent specialists serve repair and industrial gas turbine customers across the continent. This mix gives the region depth in both flight and ground-based applications. Close ties between engine makers and universities also keep a steady flow of process improvements moving into production lines.
Emissions regulation and climate targets push European operators toward higher efficiency turbines, including units designed for hydrogen blends. Academic and industry consortia are researching high-entropy oxides, CMAS resistance and hydrogen compatibility for next-generation coatings. The United Kingdom is the faster growing national market in the region according to published assessments, helped by its engine service sector. Supply security for rare earths has become a strategic topic across European procurement teams. Procurement teams are weighing longer stock cover and second-source powder qualification to protect production schedules.
⮞For instance, in January 2026 EUROCONTROL reported that 11.12 million flights operated across the European network in 2025, an increase on 2024. Heavier flight schedules accelerate engine wear and bring forward the recoating of turbine blades.
Latin America and MEA Thermal Barrier Coatings Market Insights
Latin America holds 6.78% of the market. Brazil leads on the strength of business jet and regional aircraft production alongside a growing thermal power fleet. Mexico belongs to this region and contributes turbo parts coating in the Bajio manufacturing belt, which serves automotive supply chains. Argentina adds demand through heavy-fuel power units. Local coating capacity is limited, so many operators ship components to North American or European service centers. That outflow indicates room for regional investment as aircraft and power fleets grow.
Middle East and Africa accounts for 6.48% of the market. Gas turbine aftermarket work across the Gulf states drives the bulk of regional demand, with Saudi Arabia expanding combined cycle capacity. South Africa contributes industrial and mining related thermal spray activity. Operators in hot and dusty settings face severe CMAS attack, which creates interest in advanced zirconate coatings and locally based repair centers. Rising air traffic through Gulf hubs adds fleet maintenance demand over the coming decade. National localization programs for energy services are also encouraging regional coating capacity.
⮞In March 2026, the U.S. Department of Commerce reported that Brazil's capacity reserve auction contracted about 19 GW of firm capacity with gas plants dominating the awards. New gas projects scheduled for 2028 to 2031 will need coated turbine hot sections.
Market Dynamics
Growth Drivers: Rising aircraft and engine output together with gas turbine additions are raising demand for protective ceramic coatings.
Fuel economy rules push engine designers toward higher turbine inlet temperatures, and each increase raises the coating burden on hot-section metals. Narrowbody and widebody build rates are rising as airlines renew fleets, and spare parts programs keep recoating shops busy. Power utilities are adding combined cycle and peaking capacity to firm up variable renewable output, and those machines depend on coated buckets and nozzles for efficiency. Marine and defense fleets extend this base through gas turbine propulsion programs and engine life extension work.
Automotive efficiency goals add another layer as turbochargers and exhaust components adopt heat management coatings. Hypersonic research in several countries is creating early demand for ultra-high-temperature ceramics. Work on nanostructured ceramics and hydrogen-ready turbine designs also widens the technical scope, since new combustion regimes impose higher heat flux on liners and blades. Together these threads give the market breadth beyond a single end use and reduce dependence on any one engine program. Suppliers with multi-industry portfolios are best placed to benefit.
⮞Embraer reported in January 2026 that it delivered 155 executive jets in 2025, the highest total in 15 years. Business aviation output of this kind adds to the stream of newly coated engine parts and the later overhaul cycle.
Restraints: Volatile yttrium and zirconia costs and the capital intensity of coating lines are limiting adoption among smaller operators.
Raw material prices swing widely because supply of yttrium and other rare earths is concentrated in a few producing countries. Export licensing and trade limits can disrupt deliveries to coating shops, and buyers have limited ability to substitute without requalification. Zirconia pricing adds further variability. Long-term service contracts can delay cost pass-through, which compresses margins. Those pressures weigh most on independent coaters that lack the purchasing scale of large engine makers. Inventory buffers help only for a limited period. Qualification cycles in aerospace extend the time needed to switch suppliers.
Plasma spray and EB-PVD equipment require heavy capital outlay and skilled operators, which limits entry for smaller repair shops. Environmental rules on dust and emissions from spray booths add compliance cost. Complex part geometries complicate recoating and raise scrap risk. Alternative insulation solutions such as refractory linings and cooled designs are chosen where cost matters more than peak temperature. Cyclical weakness in end markets such as automotive can also slow orders at times. Together these factors moderate the pace at which new entrants can build capacity.
⮞The International Organization of Motor Vehicle Manufacturers reported in April 2026 that vehicle production in the Americas fell 2.1% in 2025. Softer output in mature regions tempers volume gains for automotive coating applications even as demand for efficient engines rises.
Opportunities: Hydrogen-capable turbines and hypersonic programs are opening room for next-generation ceramic and smart coating systems.
Hydrogen combustion raises flame temperatures and water vapor loads, so turbine makers need coatings that withstand both. That creates a development path for advanced zirconates and environmental barrier layers that protect ceramic matrix composite parts. Yttrium aluminum garnet variants aimed at inlet temperatures near 1,700 degrees Celsius are under study in public research programs. Hypersonic vehicles require coatings that survive extreme heat flux, a requirement that may open contract work for specialist coaters. Early suppliers could secure long-term positions in these programs.
Emerging markets add geographic opportunity. Gas turbine projects in Asia Pacific and the Middle East need local coating and repair capacity, while India is building private aerospace spray shops under expanding manufacturing programs. Additive manufacturing is enabling new part shapes that will require tailored coatings. Smart coatings with embedded sensors may let operators monitor temperature and wear in service, supporting condition-based maintenance and premium pricing for suppliers. Service providers that combine coating with digital inspection stand to differentiate their offers from commodity spray shops.
⮞As of December 2025, India's Central Electricity Authority recorded 20.12 GW of gas-based installed capacity. A gas fleet of that size requires continuous hot-section refurbishment, which opens a service market for regional coaters.
Recent Developments:
-
August 2025, Chromalloy opened a new EB-PVD thermal barrier coating system at its Belac Coatings Center of Excellence in Oldsmar, Florida. The system supports hot-section airfoil parts manufacturer approval repairs. The addition expands electron beam capacity for North American aftermarket customers.
-
December 2025, Linde AMT acquired the Equipment and Parts Division of Kermetico Inc., which includes HVAF thermal spray systems sold under the TAFA and Genie names. The purchase broadens its thermal spray equipment range. It also reflects consolidation among suppliers of spray hardware.
-
May 2025, GE Vernova announced that it will supply five 7HA gas turbines for the 3 GW expansion of the Qurayyah power plant in Saudi Arabia. The order comprises three 7HA.03 and two 7HA.02 units. Each H-class machine carries coated hot sections, so the project adds to Middle East coating and service demand.
-
March 2025, Siemens Energy secured a contract for the Rumah 2 and Nairyah 2 power plants in Saudi Arabia with a combined capacity of 3.6 GW. The agreement includes a 25-year service arrangement and components from the Dammam Hub. Long-term service work of this kind supports recurring coating and refurbishment demand.
Thermal Barrier Coatings Market Key Players
-
Oerlikon Metco
-
Linde AMT
-
Honeywell Aerospace
-
Chromalloy
-
MTU Aero Engines
-
Saint-Gobain Coating Solutions
-
Sulzer
-
Zircotec
-
Metallisation
-
Turbine Surface Technologies
-
Treibacher
-
Hoganas
Thermal Barrier Coatings Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 19.58 Billion |
| Market Size by 2035 | USD 35.90 Billion |
| CAGR | CAGR of 6.25% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Metals, Ceramics, Intermetallics, and Others) • By Application (Stationary Power Plants, Aerospace, Automotive, and Others) • By Technology (Cold Spray, Flame Spray, Plasma Spray, High-Velocity Oxy-Fuel (HVOF) Spray, and Electric Arc Spray) • By Coating Material (Ceramic Yttria-Stabilized Zirconia (YSZ), Aluminum Oxide (Al₂O₃), MCrAlY (Metallic Bond Coat), Mullite-Based Coatings, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Oerlikon Metco, Linde AMT, Honeywell Aerospace, Chromalloy, MTU Aero Engines, Saint-Gobain Coating Solutions, Sulzer, Zircotec, Metallisation, Turbine Surface Technologies, Treibacher, Hoganas |
Frequently Asked Questions
Key players in the Thermal Barrier Coatings Market include Oerlikon Metco, Linde AMT, Honeywell Aerospace, Chromalloy and Saint-Gobain Coating Solutions, among others.
Key opportunities include hydrogen-capable gas turbines, hypersonic programs, advanced rare-earth zirconate and garnet coatings, smart sensor-embedded coatings and new repair capacity in Asia Pacific and the Middle East.
The major growth factor is the push for higher turbine inlet temperatures in aircraft engines and gas turbines, which raises fuel efficiency and requires ceramic coatings to protect hot-section metals and extend overhaul intervals.
The Aerospace segment dominated the Thermal Barrier Coatings Market with approximately 44.05% share in 2025, supported by large engine fleets and recurring overhaul demand.
Asia Pacific dominated the Thermal Barrier Coatings Market in 2025 with approximately 35.23% share, owing to aircraft assembly growth, large power build-outs and expanding vehicle production across China, Japan, South Korea and India.
