
Laboratory Information Management System Market Report Scope & Overview:
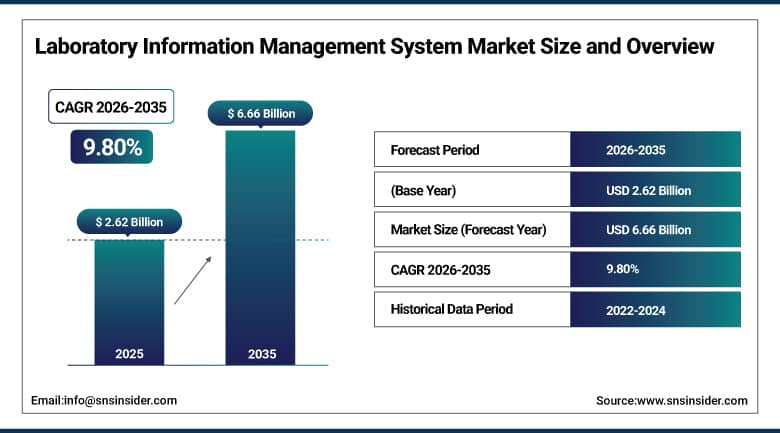
The Laboratory Information Management System Market was valued at USD 2.62 Billion in 2025 and is expected to reach USD 6.66 Billion by 2035, growing at a CAGR of 9.80% from 2026-2035.
The Laboratory Information Management System (LIMS) Market covers software and related services that track samples, tests, instruments, reagents, results and reports across a laboratory. Pharmaceutical and biotechnology companies, contract research and manufacturing organizations, clinical laboratories, and food, environmental and industrial testing laboratories use LIMS to maintain data integrity, shorten turnaround times and prepare for audits. Services, including implementation, validation and support, hold the largest share because most deployments need substantial configuration, while cloud-based software is growing as laboratories move away from local servers. Regulatory expectations for electronic records and the push to connect instruments and analytics are supporting steady demand. North America leads the market, while Asia Pacific is expected to grow at the fastest pace.
⮞In May 2026, a survey of 110 quality assurance and quality control laboratories conducted by 1LIMS found that 95% use digital tools but only about one in five consider themselves fully digital, and 54% still use spreadsheets every day. The result shows how much room remains for laboratories to replace manual records.
To Get More Information On Laboratory Information Management System Market - Request Free Sample Report
Laboratory Information Management System Market Trends
-
Migration of laboratory systems from on-premise servers to cloud-hosted software-as-a-service platforms
-
Use of AI assistants to configure workflows, review results and flag anomalies
-
Convergence of LIMS with electronic lab notebooks, scientific data management and instrument integration tools
-
Growth of industry-specific LIMS tailored to cell and gene therapy, clinical and food testing laboratories
-
Stronger focus on data integrity, audit trails and validated electronic records
U.S. Laboratory Information Management System Market Outlook
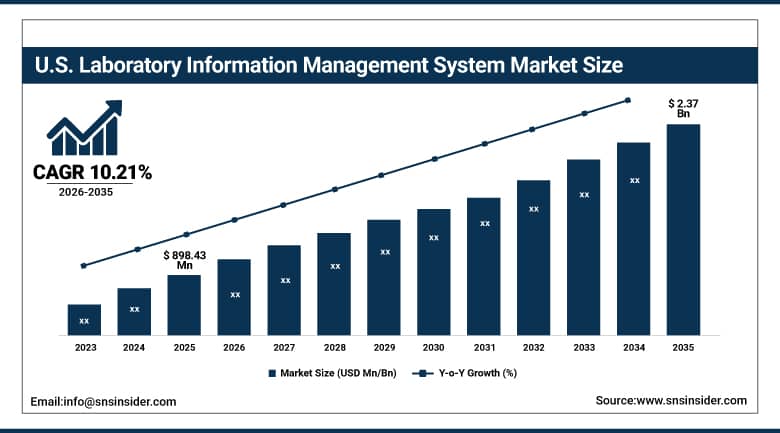
The U.S. Laboratory Information Management System Market was valued at USD 898.43 Million in 2025 and is expected to reach USD 2.37 Billion by 2035, growing at a CAGR of 10.21% from 2026-2035.
The U.S. Laboratory Information Management System Market is the largest national market for laboratory informatics, supported by a dense base of pharmaceutical and biotechnology companies, contract research organizations, hospital and reference laboratories, and industrial testing facilities. Food and Drug Administration (FDA) rules on electronic records, Clinical Laboratory Improvement Amendments (CLIA) requirements and customer audits push laboratories to keep validated, traceable data. Cell and gene therapy developers and clinical genomics laboratories are buying specialized systems, while established laboratories are replacing aging on-premise platforms with cloud services. Competition includes global informatics suppliers, long-established LIMS specialists and newer cloud-native entrants.
⮞For instance, in October 2026 the Centers for Medicare and Medicaid Services and the Centers for Disease Control and Prevention proposed changes to CLIA personnel and virtual access rules, with comments due on December 7, 2026.
Laboratory Information Management System Market Segment Analysis
-
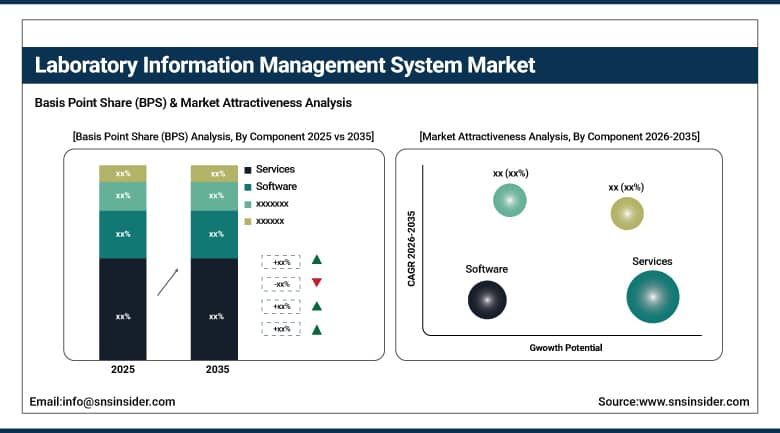
By Component, the Services segment dominated the Laboratory Information Management System Market with approximately 55.00% share in 2025, while the Software segment is the fastest growing with a CAGR of approximately 10.40%.
-
By Product Type, the Broad-Based LIMS segment dominated the Laboratory Information Management System Market with approximately 60.00% share in 2025, while the Industry-Specific LIMS segment is the fastest growing with a CAGR of approximately 10.30%.
-
By Deployment Mode, the On-Premise segment dominated the Laboratory Information Management System Market with approximately 52.30% share in 2025, while the Cloud-Based segment is the fastest growing with a CAGR of approximately 11.56%.
-
By End User, the Pharmaceutical and Biotechnology Companies segment dominated the Laboratory Information Management System Market with approximately 43.89% share in 2025, while the Contract Research and Manufacturing Organizations segment is the fastest growing with a CAGR of approximately 11.62%.
By Component, Services Dominates the Laboratory Information Management System Market and Software Grows Fastest
Services hold the largest share because a LIMS is rarely used as installed. Each laboratory has its own sample types, test methods, specifications and reporting formats, so vendors and consultants spend considerable effort on workflow design, instrument interfaces, data migration, validation and training. Regulated laboratories must document validation for every release, and upgrades often require repeat testing. Support contracts, hosting, and managed services then provide recurring income long after the first project, which keeps the services component ahead of license revenue. Customers also pay for training, documentation and periodic revalidation, so each laboratory typically spends several times the license value on services over the life of a system.
Software is growing fastest as vendors package configurable platforms that reduce custom work. Cloud subscriptions, prebuilt templates for common laboratory types and low-code configuration tools allow customers to go live faster and to upgrade without large projects. Artificial intelligence features, including assistants that build workflows and review results, are being added to the core product. Integration with electronic lab notebooks, instruments and enterprise systems also increases the value of the software license in each contract. Managed hosting and outsourced administration are also growing, since many laboratories prefer to leave patching, backups and uptime to the vendor. Hardware such as barcode printers, scanners and instrument interfaces forms a small part of many projects but adds to the services work that vendors perform.
⮞In August 2025, LabConnect deployed Sapio LIMS across its global operations, covering more than 30 locations and over 5,000 validated tests.
By Product Type, Broad-Based LIMS Dominates the Laboratory Information Management System Market and Industry-Specific LIMS Grows Fastest
Broad-based LIMS holds the largest share because these platforms serve many kinds of laboratories with one configurable core. Large companies with several laboratory types prefer a single system that can handle sample tracking, testing, inventory and reporting across sites. The platform approach also lets customers add modules over time and reuse validated components, which lowers training and maintenance effort. Vendors with long track records in manufacturing quality control, research and environmental testing have large installed bases that renew steadily. Instrument vendors and enterprise software suppliers also bundle general-purpose LIMS modules with their offerings, which keeps the broad-based category widely used.
Industry-specific LIMS is growing fastest as laboratories seek systems designed for particular regulations and workflows. Clinical and public health laboratories need patient-linked results and billing, cell and gene therapy developers need chain-of-identity tracking, and food and water testing laboratories need method-based compliance. Preconfigured editions shorten implementation and reduce validation effort. Vendors are therefore releasing editions for specific industries, which increases adoption among mid-sized laboratories that lack large informatics teams. Laboratory-specific editions often reuse the same core code, so vendors can add new industries without rebuilding the platform from scratch. Customers that begin with a broad core often add specialized modules later, which allows vendors to grow revenue within existing accounts.
⮞In June 2026, China's National Medical Products Administration set a single procedural framework for device reclassification, including in vitro diagnostic reagents, with Announcement No. 52 of 2026 taking effect on June 1.
By Deployment Mode, On-Premise Dominates the Laboratory Information Management System Market and Cloud-Based Grows Fastest
On-premise installations lead because many laboratories invested in local servers, validated them and integrated them with instruments and legacy systems. Pharmaceutical, defense and government laboratories often have strict data policies and prefer to keep records within their own networks. Replacing a validated system is costly and risky, so many organizations continue to upgrade existing installations. Instruments and software also run in controlled environments where network access is limited, which supports local deployment. Vendors still support on-premise customers with regular releases, and hybrid models in which local instruments feed a cloud analytics layer are common.
Cloud-based delivery is growing fastest as vendors offer validated software-as-a-service platforms that avoid hardware costs and simplify upgrades. Smaller laboratories, startups and contract organizations adopt the cloud first, since they lack information technology staff. Large companies are moving selected laboratories to hosted environments and using cloud analytics across sites. Vendors have strengthened security certification and validation packages, which addresses past concerns about regulated data. Pricing based on users or samples also lets laboratories scale spending with workload, which is helpful for organizations with seasonal peaks. Regulators in several countries have also issued guidance on cloud validation, which gives laboratories clearer expectations for compliance.
⮞The International Laboratory Accreditation Cooperation transition period for ISO 15189:2022 ended in December 2025, three years after the standard was published, so laboratories still accredited to the 2012 edition lose recognition under the mutual recognition arrangement.
By End User, Pharmaceutical and Biotechnology Companies Dominates the Laboratory Information Management System Market and Contract Research and Manufacturing Organizations Grows Fastest
Pharmaceutical and biotechnology companies account for the largest share because they run many regulated laboratories for research, quality control, stability testing and release. They need validated systems, strict audit trails and links to manufacturing and quality management software. Large budgets and global operations support enterprise licenses, and growth in biologics, cell therapy and specialty drugs adds new testing workflows. Companies also replace older systems when they consolidate sites or acquire new laboratories. Quality control laboratories attached to production lines add routine volume, and their need to release batches quickly favors integrated systems.
Contract research and manufacturing organizations are growing fastest as drug developers outsource more testing and production. These firms serve many clients with different requirements, so they need flexible systems that separate data, handle varied methods and meet audits from several customers. Clinical and diagnostic laboratories form another large group, driven by genomics and test volume growth. Food, environmental, chemical and oil and gas laboratories add steady demand for compliance and throughput. Academic research institutes, public health agencies and environmental testing laboratories add smaller but steady demand, often through grants and public tenders. Veterinary, forensic and agricultural laboratories also add specialized demand that vendors serve with tailored configurations.
⮞On March 3, 2026, the FDA issued Warning Letter 320-26-47 to Tentamus India, citing torn analytical records found in two garbage bags and five pre-signed maintenance records.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
80.80 |
|
Europe |
Germany |
22.14 |
|
Asia Pacific |
China |
36.52 |
|
Latin America |
Brazil |
47.38 |
|
Middle East & Africa |
Saudi Arabia |
30.91 |
North America Laboratory Information Management System Market Insights
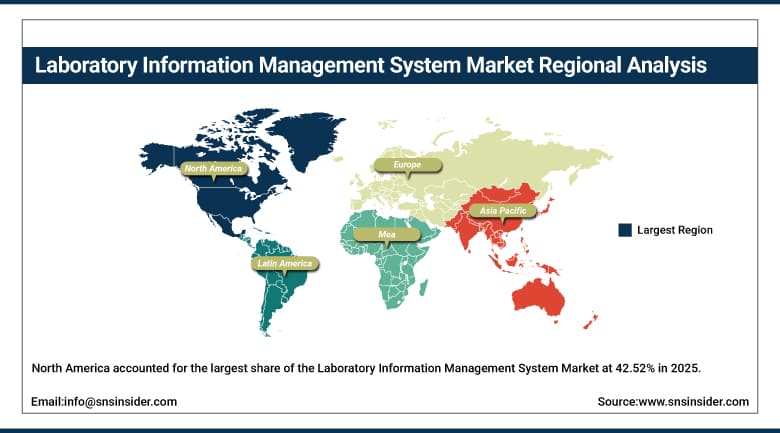
North America accounted for the largest share of the Laboratory Information Management System Market at 42.52% in 2025, led by the United States with a smaller contribution from Canada. A large pharmaceutical and biotechnology industry, many contract research organizations and strict data integrity expectations create steady demand. Leading LIMS vendors are headquartered in the region, which supports a competitive supply base. Reference laboratories and hospital networks are also consolidating systems, which creates large replacement projects for established vendors.
Clinical and public health laboratories are replacing older systems with cloud-based platforms, and cell and gene therapy developers are buying specialized editions. The regulatory picture for laboratory-developed tests has changed, easing uncertainty for clinical laboratories planning informatics investment. Canadian laboratories are modernizing provincial networks and research facilities. Pharmaceutical manufacturers in the region are also expanding domestic production, which adds new quality control laboratories that need validated systems from the start.
⮞On September 19, 2025, the FDA formally rescinded its laboratory-developed test final rule in the Federal Register, restoring the text of 21 CFR 809.3(a).
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Laboratory Information Management System Market Insights
Europe is a large and mature region led by Germany, the United Kingdom, France, Switzerland and Italy. A strong pharmaceutical, chemical and food industry, together with public health laboratories, supports demand. Laboratories follow ISO standards closely, and several leading LIMS and clinical laboratory suppliers are based in the region. Consolidation of pathology services and public tenders for regional laboratory networks are also shaping vendor selection across several countries.
The in vitro diagnostic regulation affects clinical laboratories and manufacturers, increasing the need for documented processes and traceability. Cloud adoption is advancing but is influenced by data protection rules and customer preference for European hosting. National health systems are consolidating laboratory networks, which creates projects to unify systems. Cross-border pharmaceutical supply chains also encourage harmonized systems, since quality data must be shared between sites in different countries. Biobank and genomic research programs in the Nordic countries and the Netherlands also require advanced sample tracking, supporting premium products.
⮞In December 2025, the European Commission published a proposal to simplify the medical device and in vitro diagnostic regulations, with the transition for in vitro diagnostics running to the end of 2027, 2028 or 2029 depending on risk class.
Asia Pacific Laboratory Information Management System Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 11.40% during 2026-2035. China, India, Japan, South Korea and Australia are expanding pharmaceutical manufacturing, contract research, clinical testing and food safety programs. Governments are strengthening laboratory accreditation, and companies are modernizing quality systems to meet global customer expectations. Contract development and manufacturing capacity in India, China and South Korea is also growing quickly, which supports purchases by service providers.
China's regulators continue to issue new standards for medical devices and diagnostics, raising documentation expectations. India is building digital health infrastructure that links laboratories to national records, and Southeast Asian countries are growing as manufacturing and testing hubs. Price-sensitive buyers in the region favor cloud subscriptions that avoid large upfront outlays. Food safety and environmental monitoring programs also add demand, as governments tighten testing requirements for exports and domestic markets.
⮞On March 17, 2026, China's National Medical Products Administration issued 26 medical device standards through Announcement No. 24 of 2026, 22 of which take effect on March 1, 2027.
MEA & Latin America Laboratory Information Management System Market Insights
In Latin America, Brazil, Mexico, Argentina and Colombia lead demand. Regulators are updating rules for diagnostics and laboratories, and private laboratory chains are investing in informatics to expand networks. Currency swings and budget limits slow purchases, but contract manufacturing and food export testing support steady demand. Large private laboratory chains in Brazil and Mexico also lead adoption, using informatics to manage networks of collection points. Telehealth and decentralized sampling projects in the region also create demand for systems that can track samples collected outside laboratories.
⮞In December 2025, Brazil's health regulator ANVISA published a regulatory agenda with 161 topics, including 38 new items and a review of in vitro diagnostic regulation, effective from January 1, 2026.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Qatar, Egypt and South Africa lead demand. Gulf governments are investing in digital health and accredited laboratory networks, while pharmaceutical localization programs create new quality control laboratories. In much of Africa, donor funding drives laboratory strengthening projects, and funding limits slow deployment of advanced systems. Pharmaceutical localization programs in the Gulf are also creating new quality control laboratories that adopt modern systems from the start.
⮞On June 2, 2026, the Abu Dhabi Quality and Conformity Council launched Mawthooq, a digital platform for delegated and accredited laboratories with more than 10 specialized digital services.
Market Dynamics
Growth Drivers: Regulatory Data Integrity Requirements, Laboratory Digitization and AI Adoption Drive Growth in the Laboratory Information Management System Market
Regulation and customer audits are the strongest drivers. Pharmaceutical, medical device, food and clinical laboratories must keep accurate, traceable and tamper-evident records, and regulators increasingly cite poor data practices in inspection findings. A LIMS provides audit trails, electronic signatures, controlled access and validated workflows, so laboratories see it as a basic requirement rather than a convenience. Competition among vendors on cloud validation packages also lowers the effort needed to meet inspection expectations, which widens the buyer base.
Digitization and automation add momentum. Laboratories are connecting instruments, robots and analytics tools, and these connections depend on a central system that tracks samples and results. Artificial intelligence offers further gains, with assistants that configure workflows, check results and identify trends. Rising test volumes in genomics, biologics and food safety increase the pressure to replace spreadsheets and paper records. Investments by drugmakers in biologics, cell therapy and genomic testing also raise sample volumes and the complexity of the data that laboratories must manage.
⮞LabVantage launched its CORTEX agentic AI offering on March 5, 2026, citing a survey in which more than 75% of laboratories plan to adopt AI and machine learning within two years.
Restraints: High Implementation Costs, Validation Burden and Limited Funding Restrain Growth in the Laboratory Information Management System Market
A LIMS project is expensive and time-consuming. Configuration, data migration, interface development and validation require specialized staff, and projects in regulated laboratories can take many months. Costs for licenses, hosting, support and upgrades continue after go-live, and smaller laboratories often struggle to justify the budget. Some organizations delay replacement of aging systems because disruption to testing is a risk. Customer concerns about the effort of revalidating systems after each major upgrade also make some laboratories postpone modernization for years.
Funding and skills gaps are further constraints, especially in developing regions. Public and donor-funded laboratories often lack budgets for informatics, and local support for advanced systems can be thin. Concerns about data security, vendor lock-in and difficulty switching platforms also slow decisions. Differences in standards across countries complicate global rollouts for multinational companies. A shortage of informatics specialists who understand both laboratory science and software also slows implementation and raises consulting costs.
⮞In July 2026, the African Society for Laboratory Medicine reported that donors fund over 90% of an estimated USD 700,000 budget for laboratory information management systems in the countries it tracks.
Opportunities: Cloud Migration, Digital Health Integration and Cell and Gene Therapy Testing Create Opportunities in the Laboratory Information Management System Market
Cloud migration offers vendors a route to recurring revenue and wider reach. Smaller laboratories that could not afford on-premise systems can adopt validated software-as-a-service platforms, and large companies are moving selected sites to hosted environments. Subscription models also allow vendors to deliver improvements continuously and to bundle analytics and AI features. Partnerships between informatics vendors and instrument makers could simplify connections and reduce the engineering effort that laboratories currently carry.
Integration with national digital health systems and new therapy areas create further openings. Governments linking laboratories to health records need compatible systems, and developers of cell and gene therapies need chain-of-identity tracking and specialized workflows. Emerging economies expanding testing capacity and accreditation programs represent additional demand for scalable, affordable platforms. Contract laboratories that win new clients often need to scale systems quickly, which favors vendors with rapid deployment options.
⮞On July 6, 2026, India's Ministry of Health reported more than 100 crore health records linked under the Ayushman Bharat Digital Mission, with an incentive scheme paying diagnostics laboratories and pharmacies for digital participation.
Recent Developments:
-
In March 2026, Dedalus launched its next-generation Dedalus LIMS to modernize pathology and diagnostics. The product supports customer upgrades from earlier platforms.
-
In October 2026, Clinisys introduced an open, governed AI platform strategy covering laboratory data, analytics, agents and workflow. The strategy builds on its Clinisys Laboratory Solution.
-
In March 2026, Thermo Fisher Scientific completed the acquisition of Clario Holdings, a provider of clinical trial endpoint data. The deal expands its offerings for pharmaceutical customers.
-
In March 2026, LabWare reported that its software-as-a-service ASSURE LIMS could be deployed in under 30 days. The platform is validated for ISO 17025 and 21 CFR Part 11 compliance.
Laboratory Information Management System Market Key Players
-
LabVantage Solutions Inc.
-
LabWare
-
STARLIMS Corporation
-
Clinisys
-
Sapio Sciences
-
Dedalus S.p.A.
-
Thermo Fisher Scientific Inc.
-
Autoscribe Informatics
-
CloudLIMS
-
LabLynx, Inc.
-
Soft Computer Consultants, Inc. (SCC Soft Computer)
-
1LIMS
-
LabKey
-
Agilent Technologies, Inc.
-
Illumina, Inc.
-
Labworks LLC
-
LIMS IQ (BGA Soft)
-
Ovation
-
Genemod, Inc.
-
Benchling, Inc.
Laboratory Information Management System Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.62 Billion |
| Market Size by 2035 | USD 6.66 Billion |
| CAGR | CAGR of 9.80% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Services and Software) • By Product Type (Broad-Based LIMS and Industry-Specific LIMS) • By Deployment Mode (On-Premise and Cloud-Based) • By End User (Pharmaceutical and Biotechnology Companies, Contract Research and Manufacturing Organizations, Clinical and Diagnostic Laboratories, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | LabVantage Solutions Inc., LabWare, STARLIMS Corporation, Clinisys, Sapio Sciences, Dedalus S.p.A., Thermo Fisher Scientific Inc., Autoscribe Informatics, CloudLIMS, LabLynx, Inc., Soft Computer Consultants, Inc. (SCC Soft Computer), 1LIMS, LabKey, Agilent Technologies, Inc., Illumina, Inc., Labworks LLC, LIMS IQ (BGA Soft), Ovation, Genemod, Inc., Benchling, Inc. |

Frequently Asked Questions
Key players include LabVantage, LabWare, STARLIMS, Clinisys, Sapio Sciences, Dedalus, Thermo Fisher Scientific, Autoscribe Informatics, CloudLIMS, LabLynx, SCC Soft Computer, 1LIMS, LabKey, Agilent, Illumina, Labworks, LIMS IQ, Ovation, Genemod and Benchling.
Key opportunities include cloud migration, integration with digital health systems, specialized platforms for cell and gene therapy, and expansion of accredited laboratories in emerging economies.
Regulatory data integrity requirements, laboratory digitization and the adoption of AI are the main growth factors, supported by rising test volumes in genomics, biologics and food safety.
By Component, the Services segment dominated the market in 2025 with an estimated 55.00% share, because configuration, validation and support are needed for almost every deployment.
North America dominated the market with a share of 42.52% in 2025, driven by a large pharmaceutical industry, many contract research organizations and strict data integrity expectations.
